top of page

Smiling woman writes a checked to-do list at a home desk with laptop, coffee, books and plants; note says End of Day Tasks

Most business owners do not really end their month, they just let it trail off and roll into the next one. The trouble is, a month that never gets closed never gets understood. You lose the chance to see clearly what happened, celebrate what worked, catch what slipped, and start the next month on solid ground. The women who feel calmest and most in control are almost always the ones who treat the end of the month as a small, deliberate ritual rather than an afterthought.


Closing your month does not have to be complicated or take hours. It is really just a checklist you run once, and the payoff is enormous: you end every month knowing exactly where you stand instead of guessing. Below are 35 things to do before you close out your business month, grouped so you can move through them easily. You will not need every single one every month, but treat this as your complete menu. And if you'd like a clean place to work through it, the free Money Mastery Net Worth Tracker gives you a simple month-end structure to follow alongside this list.


Record and Reconcile

  1. Record every payment you received this month.

  2. Record every expense you paid this month.

  3. Match your records against your bank statement.

  4. Match against your business card statement too.

  5. Catch any transaction you forgot to log.

  6. Flag anything unfamiliar on your statements.

  7. Confirm every deposit actually landed.

  8. Note any pending transactions not yet cleared.


Check the Money Owed and Owing

  1. List every unpaid invoice clients still owe you.

  2. Send friendly reminders on any overdue invoices.

  3. Note any invoice that has gone unusually quiet.

  4. List every bill you still owe others.

  5. Confirm no bill is slipping past its due date.

  6. Check for any recurring charge that shouldn't still be active.


Run Your Core Numbers

  1. Add up your total money in for the month.

  2. Add up your total money out for the month.

  3. Calculate your profit for the month.

  4. Compare this month's profit to last month's.

  5. Note your best income source this month.

  6. Note your biggest expense this month.

  7. Check your current cash cushion.


Handle Pay, Taxes, and Set-Asides

  1. Confirm you paid yourself this month.

  2. Confirm your tax set-aside was moved.

  3. Move any savings or reserve transfers you planned.

  4. Check your tax set-aside is on track for the year.

  5. Confirm any owner-pay you owe yourself is complete.


Review and Learn

  1. Note one thing that went well this month.

  2. Note one thing that surprised you.

  3. Spot any expense creeping up over recent months.

  4. Check whether your income trend is rising or dipping.

  5. Note any pricing that felt too low this month.


Set Up for a Clean Start

  1. File or save this month's receipts and records.

  2. Update any running spreadsheet or tracker.

  3. Write down one money goal for next month.

  4. Put your next month-end close on the calendar.


How to Close Out Your Business Month: A Real Example

Smiling woman at a home desk opens a MacBook beside coffee and notes; a MONTH-END SUMMARY sheet, plant, and window glow in warm light.

Let me show you how quick and clarifying this can be.


It is the last day of the month, and you sit down with your tea and the checklist. You record your final transactions and reconcile against your statements, catching one expense you forgot to log (items 1 through 8). You see two invoices still unpaid, so you send two quick friendly reminders (items 9 and 10). You run your core numbers: $5,400 in, $3,900 out, so $1,500 profit, which you notice is up from last month's $1,200 (items 15 through 18). You confirm you paid yourself and moved your tax set-aside (items 22 and 23).


Then you take five minutes to learn from it. You notice one subscription has crept up two months running and flag it to review, and you notice your income is trending up nicely (items 29 and 30). You file your records, write down a goal for next month, aim for $6,000 in income, and put next month's close on your calendar (items 32 through 35). Twenty minutes, start to finish, and you now know exactly where your business stands, what worked, and what to watch. Compare that to the vague uncertainty of just letting the month slide by, and the difference in how you feel is night and day.


Cozy desk with notebook titled Spending Audit, a laptop and tablet showing Financial Dashboard charts, plus coffee and almonds.

That calm, clear feeling at month-end is exactly what the Money Mastery community helps women build into a steady habit. If you would like help setting up a month-end routine that fits your business, you can schedule a call with a coach who has 20 years of business coaching experience and build your own simple close.


To make running your core numbers effortless each month, the free Money Mastery net worth tool keeps your full picture in one place so month-end is a quick glance rather than a scramble.


Closing out your month is one of the simplest habits with one of the biggest payoffs. It turns the end of every month from a blur into a moment of real clarity, and it lets you start each new month standing on solid ground instead of guessing where you are. Run the checklist, and give yourself the gift of always knowing. If you'd like help deciding which parts to prioritize first, the upcoming Money Clarity Assessment can point you to your most valuable month-end habits.


About Donna Roggio

Donna Roggio is the founder of the Money Mastery system and has spent 20 years helping women build real financial clarity and confidence in their businesses. She created Money Mastery to give women a supportive community and a simple, learnable way to understand their money, without shame, jargon, or overwhelm. Donna believes every woman can learn to run her numbers with confidence, and she is here to help you do exactly that.

Frequently Asked Questions

How do I close out my business month?

Run a simple checklist: record and reconcile all transactions, check money owed to you and by you, calculate your core numbers, confirm your pay and tax set-asides, review what you learned, and set up a clean start for next month. It usually takes under half an hour once it is a habit.


Why should I close out my business month?

A month that never gets closed never gets understood. Closing it lets you see clearly what happened, celebrate what worked, catch what slipped, and start the next month on solid ground instead of guessing where you stand.


How long does a monthly close take?

For most small businesses, about twenty to thirty minutes once you have a routine. Keeping up with your records weekly makes the monthly close even faster.


What is the most important part of closing the month?

Reconciling your records against your statements and running your core numbers are the foundation, since they tell you exactly where you stand. The free Money Mastery Net Worth Tracker gives you a simple month-end structure to follow.

Smiling woman at a wooden desk writes in a yellow notepad beside a mug, phone, and papers in a cozy home office.

Let me start by taking something off your shoulders. Business debt is not a moral failing. It does not mean you are bad with money or that you built the wrong business. Debt is a tool, and like any tool it can be used well or poorly, but carrying it does not make you a failure. So many women carry a quiet shame about debt that makes them either avoid looking at it entirely or attack it so aggressively that they starve the very business that is supposed to pay it off. Neither extreme works. What works is a plan.


Here is the mistake the panic approach makes. When debt feels frightening, the instinct is to throw every spare dollar at it, skipping your own pay, draining your cushion, cutting the things that actually generate income. That can feel virtuous, but it often weakens your business right when it needs to be strong, and a weak business struggles to pay off anything. Learning how to pay off business debt strategically means shrinking what you owe steadily while keeping your business healthy enough to keep earning. Let me walk you through it.


Step 1: Get the Full Picture Out of the Shadows

The first step is the one avoidance makes hardest: look at all of it, clearly, without flinching. You cannot make a plan for a number you refuse to see. Debt kept vague and scary in the back of your mind always feels worse than debt written plainly on a page.


List every debt: who you owe, the total balance, the interest rate, and the minimum payment. Line them up side by side. This single act often brings enormous relief, because the monster in the dark turns out to be a set of specific, manageable numbers. And it gives you the information the whole plan depends on, especially those interest rates, which tell you where your debt is quietly growing fastest. If you'd like a clean template to lay it all out, the free Money Mastery Net Worth Tracker gives you a simple structure to capture every debt in one place.


Step 2: Protect the Business First, Then Attack the Debt

This is the step that separates a strategic payoff from a panicked one. Before you send extra money to debt, make sure your business can keep running and earning. That means you still pay yourself something, you still cover your essential costs, and you still set aside your taxes. A business that stops paying its owner or skips its taxes to kill debt faster usually just creates a new emergency.


Decide on a sustainable amount you can put toward debt beyond the minimums, an amount that shrinks what you owe meaningfully without hollowing out your business. Slower and steady beats fast and fragile every time, because the goal is not to be debt-free next month at the cost of your business, it is to be debt-free while still standing strong.


Step 3: Choose Your Payoff Order Deliberately

Once you have your extra payoff amount, you need to decide where it goes first, because spreading it thinly across everything is the slowest path. There are two proven approaches, and both work, so choose the one that fits how you are wired.


The first is to target the highest interest rate debt first while paying minimums on the rest, which saves you the most money over time because it stops the fastest-growing debt from growing. The second is to target the smallest balance first, regardless of rate, which gives you a quick, motivating win and builds momentum. Whichever you choose, put all your extra money on that one debt until it is gone, then roll everything you were paying on it onto the next. This rolling focus is what makes debt fall far faster than scattered payments ever could.


Step 4: Stop the Debt From Growing Back

There is little point in paying off debt if new debt quietly takes its place, so part of any real plan is addressing why the debt appeared. Sometimes it was a deliberate, healthy investment in growth, and that is fine. But sometimes it is a sign of a gap, expenses outrunning income, no cushion for surprises, prices set too low to actually pay the business.


While you pay down what you owe, look honestly at the cause. If your prices do not cover your true costs, debt will keep filling the gap no matter how fast you pay. If a lack of any buffer means every surprise goes on a card, building even a small reserve alongside your payoff prevents the next round. Paying off debt and fixing its source at the same time is how you get free and stay free.


How to Pay Off Business Debt Strategically: A Real Example

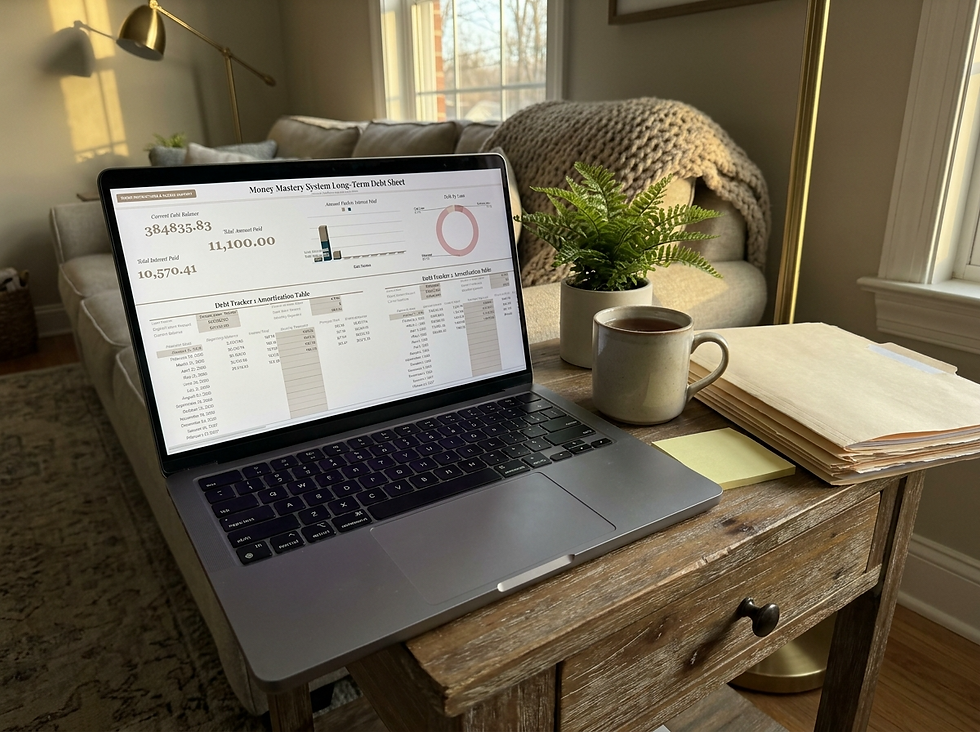
Laptop showing a debt tracker spreadsheet on a cozy living room side table, with coffee mug, plant, folders, and sticky note.

Let me put this into numbers so the plan feels real.


Say you have three business debts: a $1,000 balance at 22 percent interest, a $3,000 balance at 12 percent, and a $500 balance at 8 percent. In a panic, you might drain your cushion and skip your own pay to throw $2,000 at them this month, leaving your business gasping. Instead, you make a plan. After paying yourself a modest amount, covering essentials, and setting aside taxes, you find you can sustainably put $400 a month toward debt beyond the minimums.


You choose the highest-interest-first approach, so all $400 extra goes to the $1,000 debt at 22 percent while you pay minimums on the others. In about three months, that debt is gone, and it was the one growing fastest. Now you roll that entire $400, plus the minimum you were already paying on it, onto the $3,000 debt. Because you are now hitting it with a larger combined payment, it falls much faster than it would have. Then you roll everything onto the last debt and finish it off. Throughout, your business kept running, you kept getting paid, and your taxes stayed covered. You got free without going fragile, and that is the whole point.


A plan like this is far easier to stick to with support and encouragement, which is exactly what the Money Mastery community offers. If you would like help building a payoff plan that fits your real numbers, you can schedule a call with a coach who has 20 years of business coaching experience and map it out together.


Laptop on desk shows Money Mastery System Credit Card Debt Center, beside coffee, books, family photo, plant, and lamp.

To see how your debt fits into your whole financial picture as it shrinks, the free Money Mastery net worth tool shows you the full view, and watching your debt drop against your growing assets is one of the most motivating things you will do.


Debt handled in a panic can quietly wound your business. Debt handled with a plan becomes just another number you steadily shrink while your business keeps growing right alongside. You are not behind, and you are not stuck. You simply need a clear plan and a little support, and both are within reach. If you want help finding where to start, the upcoming Money Clarity Assessment can show you your smartest first move.

About Donna Roggio

Donna Roggio is the founder of the Money Mastery system and has spent 20 years helping women build real financial clarity and confidence in their businesses. She created Money Mastery to give women a supportive community and a simple, learnable way to understand their money, without shame, jargon, or overwhelm. Donna believes every woman can learn to run her numbers with confidence, and she is here to help you do exactly that.

Frequently Asked Questions

How do I pay off business debt strategically?

Start by listing every debt with its balance, interest rate, and minimum payment. Protect your business first by still paying yourself, covering essentials, and setting aside taxes. Then put a sustainable extra amount toward one debt at a time, and address the reason the debt appeared so it does not grow back.


Should I pay off my highest interest debt or smallest balance first?

Both work. Highest interest first saves you the most money over time. Smallest balance first gives you a quick, motivating win. Choose the one that best matches how you stay motivated, and put all your extra payment on that one debt until it is gone.


Should I stop paying myself to pay off business debt faster?

Generally no. Starving your business or skipping your own pay to kill debt quickly often creates a new emergency. A steady, sustainable payoff that keeps your business healthy usually works better than an aggressive one that weakens it.


How do I stop business debt from coming back?

Address the cause while you pay it down. If prices are too low to cover your true costs, or a lack of any buffer sends every surprise onto a card, fixing those gaps prevents the next round of debt. The free Money Mastery Net Worth Tracker helps you find and close those gaps.


Two women laugh over coffee and pastries at a wooden café table, one writing in a notebook in a bright, cozy room.

There is a quiet myth in business that the strong ones do it alone, that asking for help or wanting company somehow means you are not quite cut out for it. It is a myth that hits women especially hard, because so many are already carrying the household, the caregiving, and now the business too, and have simply gotten used to figuring everything out by themselves. But here is what the data and decades of experience both show: women who build in community do not just feel better, they build stronger, steadier, more successful businesses. Consider that the number of women-owned businesses grew more than 12 percent in just three years, a surge that has grown right alongside the rise of women's business communities, networks, and learning circles. That is not a coincidence.


The reason is simple and human. Money, in particular, is the area where isolation does the most damage, because so many women were taught to be private, even ashamed, about it. Learning why women build stronger businesses in community starts with understanding what happens to your money confidence when you finally stop carrying it alone. Let me walk you through it.


It Breaks the Isolation That Keeps Money Confusing

The first thing community does is end the silence. When you are figuring out your finances alone, every question feels like proof you should already know the answer, so you do not ask, and the confusion compounds in private. In a supportive group, you discover that the thing you were embarrassed not to understand is something nearly everyone wondered about too.


That shared honesty is transformative. A question you sat on for a year gets answered in five minutes because someone else already worked through it. The shame that made money feel heavy lifts, because you see you were never behind, you were just alone. If you want a gentle first step into that kind of support, the free Money Mastery Net Worth Tracker is a simple way to begin without any pressure.


It Turns Learning Into Something That Actually Sticks

Most people do not struggle with money because the concepts are impossibly hard. They struggle because learning alone rarely sticks. You read an article, feel briefly inspired, and by the next week the momentum is gone and nothing has changed. Community fixes the follow-through problem.


When you are learning alongside others, there is a rhythm and an accountability that solo learning simply cannot provide. You show up because others are showing up. You apply what you learn because you will talk about it next week. The steady, repeated practice that actually builds money skills becomes natural, because it is woven into a group that keeps moving together instead of a resolution you make and quietly abandon.


It Gives You Real Examples From Women Like You

Generic advice only takes you so far, because your business is specific. What accelerates real growth is seeing how someone in a situation like yours actually handled the exact thing you are facing, priced the service, had the hard client conversation, set aside the taxes, made the leap.


Community gives you a library of living examples, women a few steps ahead who show you what is possible and women a few steps behind who remind you how far you have come. This is worth more than any single expert, because it is not one path held up as the answer, it is many real paths that let you find your own. And the encouragement of watching others succeed does something no article can: it makes you believe it is genuinely possible for you too.


It Steadies You Through the Hard Stretches

Every business has hard stretches, the slow month, the lost client, the moment of doubt when quitting looks tempting. These are exactly the moments when going it alone is most dangerous, because there is no one to remind you that this is normal and it passes.


A community carries you through those valleys. Someone who has been there tells you they felt the same and kept going. Someone cheers a small win you would have dismissed. That steadying presence is often the difference between an owner who pushes through a rough patch and one who quietly gives up right before things would have turned. Resilience is far easier to sustain together than alone.


Why Women Build Stronger Businesses in Community: A Real Example


Two women discuss a business plan at a wooden table with coffee, notebook and plant in a bright home office.

Let me show you the difference with two familiar stories.


Picture the first woman. She is talented and hardworking, but she builds entirely alone. When she is confused about pricing, she guesses. When taxes overwhelm her, she avoids them until they become a crisis. When a slow month hits, she has no one to tell her it is normal, so she spirals into doubt. She is not failing for lack of ability. She is struggling because every burden is hers alone, and isolation makes every problem heavier than it needs to be.


Now picture the second woman, equally talented, but she joined a community. When pricing confuses her, she asks and gets three real answers by that afternoon. When taxes loom, she follows a rhythm the group taught her and stays ahead of them. When her slow month comes, five women tell her they had one too and it passed, so she holds steady instead of panicking. She learns faster, worries less, and builds something sturdier, not because she is more gifted, but because she is not carrying it alone. Same talent, same challenges, completely different trajectory, and the only variable is community.


That second experience is exactly what Money Mastery was created to give women, real financial learning inside a supportive community, so your business grows and you never have to figure your money out alone again. To take your first practical step, the free Money Mastery net worth tool helps you see your starting point clearly, and the upcoming Money Clarity Assessment will show you where to focus first.


Two women laughing on a cream sofa in a bright living room, with coffee mugs, a notebook, and a plant on the table.

You were never meant to build your business in isolation, and you certainly were never meant to face your money alone. The women who thrive are not the ones who need no help, they are the ones wise enough to build alongside others. Step into community, and watch how much steadier, clearer, and stronger your business becomes.


If you would like a warm first conversation about where you are and where you want to go, you can schedule a call with a coach who has 20 years of business coaching experience and take your first step in with someone by your side.

About Donna Roggio

Donna Roggio is the founder of the Money Mastery system and has spent 20 years helping women build real financial clarity and confidence in their businesses. She created Money Mastery to give women a supportive community and a simple, learnable way to understand their money, without shame, jargon, or overwhelm. Donna believes every woman can learn to run her numbers with confidence, and she is here to help you do exactly that.

Frequently Asked Questions

Why do women build stronger businesses in community?

Community breaks the isolation that keeps money confusing, turns learning into something that actually sticks through accountability, provides real examples from women in similar situations, and steadies you through the hard stretches. Together, these help women grow faster and feel more confident than they would alone.


Is it really better to learn business finances in a group?

For most people, yes. Solo learning often fades within a week, while group learning adds rhythm, accountability, and real-world examples that make the lessons stick and get applied. That follow-through is what actually builds money skills.


I feel embarrassed about not understanding money. Will community help?

Very much so. One of the first things a supportive community does is show you that nearly everyone had the same questions. The shame lifts quickly once you realize you were never behind, just alone with it.


How do I find a supportive financial community for women?

The Money Mastery program was built specifically to give women financial learning inside a supportive community. You can start with the free Money Mastery Net Worth Tracker and take your first step in.

bottom of page