top of page

Small Business Finance

Take what your largest client paid you this year and divide it by your total income. That one figure tells you how much of your business belongs to somebody else's decision.


In the example below the answer is 38%. And because the business has costs that do not shrink when a client leaves, losing her would take 47% of the profit. One email could nearly halve what the owner takes home.


A big client feels like safety. Often it is the largest risk in the business. Here is how to measure it, what the number means, and how to spread the weight without turning good work away.


Income sorted by source in the Money Mastery System

Sorted by client, the largest line is hard to miss. Example data.


The short version


  • Client concentration = your largest client's payments ÷ total income × 100.

  • The hit to profit is bigger than the hit to income, because costs stay.

  • Above about a third from one client, plan for the day she leaves.

  • The fix is not to drop her. It is to grow the rest and keep a larger cushion.


The sum


Client

Paid this year

Share of income

Client A

$36,480

38%

Client B

$19,200

20%

Client C

$14,400

15%

Everyone else

$25,920

27%

Total

$96,000

100%


Three clients provide nearly three quarters of her income, and one of them provides more than a third. If you have never done this sum, the result is usually a surprise.


Why profit falls further than income


Today

If Client A left

Income

$96,000

$59,520

Cost of running the business

$18,000

$18,000

Profit

$78,000

$41,520

Change in profit


down 47%


Income falls by 38% and profit falls by 47%. Her rent, software and insurance are the same with or without Client A, so the whole of the lost income comes out of what she keeps.


This is the mirror image of what a price rise does, and for the same reason. Fixed costs make good news better and bad news worse.


What the number means


Largest client's share

What it suggests

Under 15%

Well spread. One departure is an inconvenience.

15% to 30%

Worth watching. Keep the cushion healthy.

30% to 50%

A real dependence. Plan now for a departure.

Over 50%

Closer to a job than a business, without a job's protections.


These bands are our own way of thinking about it and not a rule. Someone with one long contract and deep savings may be comfortable at 50%. The point is to know your figure and decide on purpose.


How long would it take to replace her?


That is the practical question. If it would take four months to replace Client A's work, you need four months of the gap in hand.


Line

Amount

Profit lost each month without Client A

$3,040

Months to replace the work, estimated

4

Cushion that covers it

$12,160


A cushion sized for an ordinary slow month would not come close. Concentration is a reason to hold more than the usual amount.
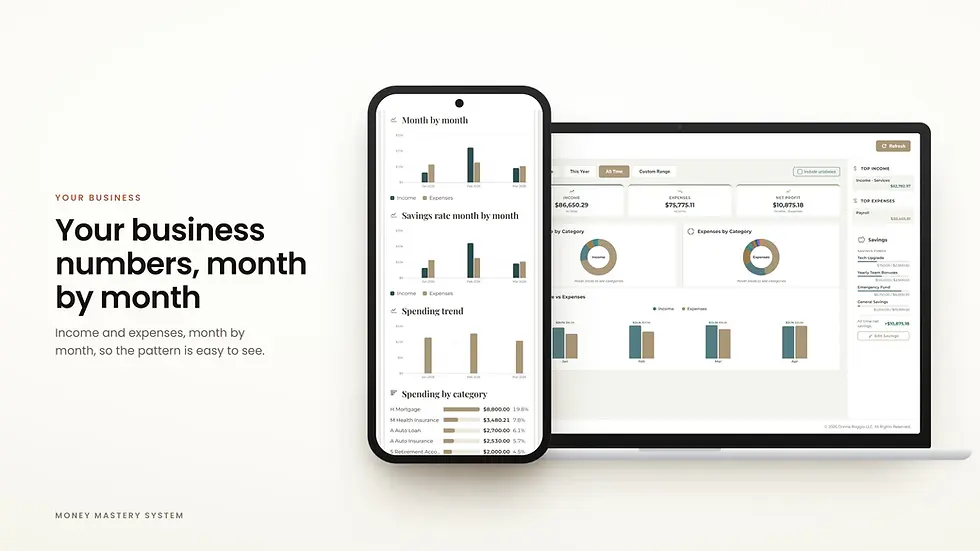

The Money Mastery System business dashboard with income by month

A departure shows up as a step down, not a dip. Example data.


Five ways to spread the weight


  1. Grow the others before you need to. Give Clients B and C a reason to do a little more with you.

  2. Keep finding new clients while you are busy. The time to look is when you do not have to.

  3. Get it in writing. A notice period in the agreement turns a sudden loss into a planned one.

  4. Hold a larger cushion. Sized to the gap and the time to replace it, as in the table above.

  5. Do not let her set your prices. A client who knows she is a third of your income may negotiate as though she owns it.


Notice that none of these is "take on less work from your best client". Good work from a good client is a gift. The aim is to make sure she is one of several legs under the table.


The quiet version of the same risk


Concentration is not only about clients. The same sum works for anything a business leans on.


  • One source of new clients, such as a single referrer or one platform.

  • One service that brings in most of the income.

  • One season that carries the year.

  • One person, which in a business of one is always you.


Run the percentage for each. Where one line is above a third, you have found the thing to protect.


A spread of clients is also one of the things that gives a business value to somebody else, as we set out in what makes a small business sellable.


See it in your own numbers, free


La Soglia, the free membership of the Money Mastery System, holds everything you own and everything you owe in one place, personal and business together, with no bank connection and no card. Income sorted by client, which is where this sum begins, is part of the paid membership.


Bring it to the Collective


What share of your income comes from your largest client? The Money Mastery Collective has a discussion feed open on the free membership. Work it out, and you will not be the only one above a third.


Questions we hear


What is client concentration?

The share of your income that comes from your largest client. Divide what she paid you by your total income and multiply by 100.

How much income from one client is too much?

There is no fixed rule. Above about a third, a single departure would change your year, so it is worth planning for.

Why does losing a client hurt profit more than income?

Because your running costs stay the same. All of the lost income comes out of what you keep.

How do I reduce dependence on one client?

Grow your other clients, keep finding new ones, put a notice period in writing, and hold a cushion sized to the gap.


References


There are no outside figures in this post. Every number is our own worked example.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. The figures and the bands are illustrations, and what level of dependence is acceptable is your own judgment. For guidance on your own circumstances, please speak with a qualified professional who knows them.

A buyer is not paying for what your business earned. She is paying for what it will keep earning after you have gone. Everything that makes a small business sellable comes back to that one idea.


Most businesses of one are never sold, and that is perfectly fine. But the same seven things that would make yours sellable also make it steadier, easier to run and less dependent on your being well every single day. They are worth building whether or not you ever sell.


Here are the seven, a simple way to score yourself, and which one to work on first.


The Money Mastery System business dashboard showing income and expenses by month

Steady months, visible on one page, are the first thing a buyer asks to see. Example data.


The short version


  • Buyers pay for income that continues without the owner.

  • Clean records for three years or more are the entry ticket.

  • One client or one person carrying the business is the biggest risk a buyer sees.

  • Each of the seven also makes the business better to own.


The seven


What a buyer looks for

Why it matters

A sign you have it

1. Income that repeats

It will still arrive next year

Retainers, memberships, regulars on a schedule

2. Clean records

The numbers can be trusted

Three years of profit you can show on a page

3. No single client carrying it

One departure cannot sink it

No client above about a fifth of income

4. Work written down

Someone else could do it

Steps for your main services on paper

5. It runs when you are away

It does not depend on you

You can take two weeks off and income continues

6. Agreements that carry over

The clients come with it

Contracts in the business name, a lease that transfers

7. A steady or rising trend

It is going somewhere

This year is at or above last year


Score yourself


Give yourself one point for each you can honestly say yes to today.


Score

What it suggests

0 to 2

The business is an income. Plan your retirement saving outside it.

3 to 4

Parts could have value. Choose one more of the seven to build.

5 to 7

A buyer might be interested. It is worth a conversation with an adviser.


A low score is not a failing. Many of the best small businesses score two, because they were built around one skilled person, and they have paid that person well for years. The point is to know which kind you have.


Where to start


With number two, clean records. It costs the least, takes the least time, and everything else depends on it. A buyer who cannot see three clear years will not look at the other six.


It is also the one that pays you back straight away, at tax time, with a lender, and every month you want to know how you are doing.


The hardest one


Number five. In a service business where clients come for you in particular, the business does not run when you are away, and no amount of paperwork changes that.


There are still ways to lean in that direction, even alone.


  1. Sell something that is not an hour of you. A recorded course, a product, a guide.

  2. Train one other person to deliver part of what you do.

  3. Move regulars to a schedule or a membership, so income is booked ahead.

  4. Write down how you do things, so a helper could step in for a fortnight.


Our earlier post on how to make your business run without you goes further into this.


Income sorted by source in the Money Mastery System

Income by client shows at a glance whether one of them is carrying the rest. Example data.


What each one does for you today


Build this

And you also get

Repeating income

Months you can plan around

Clean records

A calm tax season and easier borrowing

A spread of clients

A business that survives one goodbye

Written steps

The freedom to delegate

Time away that works

Rest, and proof the business is real

Proper agreements

Fewer disputes

A steady trend

Confidence in your own decisions


Read down the right-hand column. That is a description of a business that is pleasant to own. Selling is almost a side effect.


If you never sell


Then your retirement has to be built from what the business pays you along the way. That is the ordinary case, and there is nothing second best about it.


What matters is deciding which case you are in while there is time to act. An owner who assumes the business is her nest egg and finds at sixty that nobody will buy it has lost the years in which she could have saved.


Three mistakes


  1. Valuing it by what you put in. A buyer values what will come out.

  2. Leaving it to the last year. Clean records and repeating income take years to show.

  3. Assuming a low score is a problem. It is information, and it tells you where to put your savings.


See both sides, free


La Soglia, the free membership of the Money Mastery System, holds everything you own and everything you owe in one place, personal and business together, with no bank connection and no card. Keeping the two as separate lines is how you see what the business is worth to you and what you have built outside it.


Bring it to the Collective


What did you score out of seven? The Money Mastery Collective has a discussion feed open on the free membership, and it is a far more useful number to share than income.


Questions we hear


What makes a small business sellable?

Income that continues without the owner: repeating revenue, clean records, a spread of clients, written processes, transferable agreements and a steady trend.

Can I sell a business that depends on me?

It is difficult. A buyer is paying for future income, so a business that stops when you stop usually has little sale value.

How do I make my business more valuable?

Start with clean records for three years, then build repeating income and reduce your dependence on any one client.

What if my business cannot be sold?

Then treat it as an income and build your retirement saving outside it, from what it pays you.


References


There are no outside figures in this post. The list and the scoring are our own, offered as a way of thinking and not as a valuation.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. What a business is worth depends on the business and the buyer, and nothing here is a valuation. For guidance on your own circumstances, please speak with a qualified professional who knows them.

Growth can feel exciting long before it becomes truly effective. More leads, more activity, and more ideas often create the impression that a business is moving forward, but real progress is not measured by motion alone. The strongest business growth strategies are the ones that produce clear, sustainable results: healthier cash flow, stronger profit, better customer relationships, and a business that becomes easier to lead rather than harder to manage.


Start by Defining What Success Actually Means


Before you measure anything, you need a practical definition of success. Many business owners say they want growth, but growth can mean very different things depending on the stage of the business. For one owner, success may mean increasing recurring revenue. For another, it may mean attracting better-fit clients, improving margins, or reducing the founder's workload while maintaining income.

If your goals are vague, your measurement will be vague too. Instead of asking, Is this working?, ask more precise questions:

Are revenue increases consistent or irregular?Is profit improving along with sales?Are customer acquisition costs staying reasonable?Are current systems able to support growth without creating chaos?Is the business becoming more financially stable?

Defining success in advance also helps you avoid a common mistake: rewarding growth that looks impressive on the surface but weakens the business underneath. A surge in sales that creates delivery strain, rising expenses, or low-quality clients is not necessarily a success.


Measure More Than Revenue Alone


Revenue matters, but it is only one part of the picture. To properly assess business growth strategies, business owners need a balanced set of indicators that show financial strength, operational health, and customer quality.

A simple way to do this is to group your metrics into four categories.

Area

What to Measure

Why It Matters

Revenue

Total sales, recurring revenue, average transaction value

Shows whether demand is increasing and whether clients are spending more

Profitability

Gross margin, net profit, owner pay

Reveals whether growth is financially healthy, not just busy

Customer performance

Lead conversion, retention, repeat business, referrals

Shows whether growth is coming from the right people and lasting relationships

Operations

Capacity, fulfillment time, team workload, errors

Helps you spot strain before growth creates instability

If you only track top-line sales, you can miss critical warning signs. For example, a new offer may increase revenue while reducing margins. A successful campaign may bring in many inquiries but very few ideal clients. Strong measurement keeps you from mistaking volume for value.


Choose the Right KPIs for Your Stage of Business


Not every metric deserves equal attention. The best key performance indicators are the ones most closely tied to your current business goals. Early-stage businesses often need to focus on lead generation, conversion, and cash flow consistency. More established businesses may need to look more closely at retention, profitability by offer, and operational efficiency.

A useful KPI set usually includes a mix of leading and lagging indicators. Lagging indicators tell you what has already happened, such as last month's revenue or quarterly profit. Leading indicators help you predict future results, such as booked consultations, proposal acceptance rate, or repeat purchase activity.

Pick one primary growth goal. Examples include increasing monthly recurring revenue, improving client retention, or raising average revenue per client.Select three to five supporting metrics. Keep the list focused enough to review consistently.Set a baseline. You need to know where you started before you can judge progress accurately.Assign a review frequency. Some numbers belong in a weekly check-in, while others make more sense monthly or quarterly.

This is also where financial clarity becomes essential. Business owners who want stronger measurement often benefit from organizing their numbers in a way that is simple enough to maintain. That is one reason some women and entrepreneurs turn to Money Coaching for Women and Business Owners, where structured money conversations can help connect growth decisions to real financial outcomes rather than guesswork.


Create a Review Rhythm That Leads to Better Decisions


Measurement only matters if it shapes action. A dashboard that no one reviews will not improve your business. The goal is to create a decision-making rhythm that helps you notice patterns early and adjust with confidence.

A practical review rhythm often looks like this:

Weekly: leads, sales activity, conversion trends, cash on hand, immediate capacity issuesMonthly: revenue, expenses, profit, owner pay, retention, performance by offerQuarterly: bigger trend analysis, pricing effectiveness, market positioning, strategic priorities

During each review, ask a small set of disciplined questions:

What improved?What stayed flat?What got worse?What likely caused the change?What needs to be adjusted next?

This approach helps you avoid reactive decision-making. Instead of changing direction every time results fluctuate, you build the habit of interpreting information in context. A single slow week may mean very little. A three-month decline in conversion rate, however, deserves attention.


Know How to Interpret Results and Make Smarter Adjustments


The final step is learning how to read your results honestly. Not every successful metric means your strategy is strong, and not every disappointing number means the strategy failed. Sometimes results are distorted by timing, seasonality, pricing changes, team transitions, or inconsistent execution.

When evaluating business growth strategies, look for patterns across multiple data points rather than isolated wins or losses. If revenue rose, ask whether profit rose too. If new clients increased, ask whether retention remained stable. If demand grew, ask whether the business handled that demand well.

It is also wise to compare outcomes against effort and sustainability. A strategy that produces growth but requires constant urgency, underpricing, or personal overextension may not be worth scaling. Healthy growth should strengthen the business financially and operationally, not leave the owner depleted.

A short measurement checklist can help:

Did the strategy improve revenue?Did it improve profit or cash flow?Did it attract the right clients?Did it create repeatable results?Did it support a healthier business overall?

If the answer is mixed, that does not mean the strategy should be abandoned. It may mean the offer needs refinement, the pricing needs adjustment, or the process needs stronger follow-through. Good measurement gives you the insight to improve, not just the verdict to stop.

In the end, the best business growth strategies are measurable because they are built on clarity. When you define success well, track the right numbers, review them consistently, and respond thoughtfully, growth becomes something you can lead with intention. For business owners who want that kind of confidence, especially around the money side of growth, disciplined financial habits and informed support can make all the difference.

Written with help from Rabbit SEO

bottom of page