top of page

Self-Employed Finance

An accountant is paid for her time, and the most expensive thing you can ask her to do is sort your papers. The same return can take two hours or seven, and the difference is almost entirely in how the year arrives on her desk.


Most owners treat this relationship as a drop-off. A folder goes in during March and a return comes out in April. That works, and it leaves most of the value on the table, because a good accountant can tell you things in November that are useless to hear in April.


Here is what to send, a one page summary that does most of the work, and the questions that turn a tax preparer into an adviser.


A report ready to share with an accountant in the Money Mastery System

One clear page does more than a full folder. Example data.


The short version


  • Send totals by category, not a pile of statements.

  • Put a one page summary on top: income, expenses, profit, tax paid.

  • Talk to her once in the autumn, when there is still time to act.

  • Ask what you could do differently. It is the question that pays for the appointment.


What an organized year saves


How the year arrives

Her time

At $150 an hour

Sorted, with a summary page

2 hours

$300

Statements and a bag of receipts

7 hours

$1,050

Difference

5 hours

$750


The rate and the hours are an example, and every practice bills differently. What holds everywhere is the shape: time spent working out what a transaction was is time you are charged for, and the answers are less reliable than if you had recorded it at the time.


What to send


  1. Income, totalled by source. And any 1099 forms you received, though your own total is what counts.

  2. Expenses, totalled by category. The categories on Schedule C are a good guide.

  3. Estimated tax payments. Each one, with its date and amount.

  4. Mileage. Business miles, by date, because 2026 has two rates.

  5. Home office figures. The square footage of the space and of the home.

  6. Equipment bought or sold. What, when and for how much.

  7. Retirement and health account contributions.

  8. Anything unusual. A large one-off payment, a loan, a change in how you work.


Receipts stay with you, filed where you can find them. She needs the totals and the confidence that the receipts exist.


The one page summary


Line

Example

Income from clients

$94,000

Business expenses

$34,000

Profit

$60,000

Estimated tax paid during the year

$8,000

Business miles

6,000

Retirement contributions

$6,000

Anything that changed this year

Began renting a studio in July


Seven lines. With this on top, she knows the shape of your year before she opens anything else, and she knows where to look for what is unusual. Our post on what your accountant wishes you had tracked all year covers how to have these figures ready.


When to talk to her


When

What for

October or November

Is there anything to do before December 31? Is my set-aside enough?

January

Send the year, with the summary page

When the return is ready

Go through it together. Ask the questions below.

Before any big change

Hiring, a large purchase, a new business structure


The autumn conversation is the one most people skip, and it is the most valuable hour of the year. In April she can only tell you what happened. In November she can still change it.


A Profit and Loss report in the Money Mastery System

Income, expenses and profit for the year, already added up. Example data.


Six questions worth asking


  1. What was my total tax as a share of my profit? That is the starting point for next year's set-aside.

  2. What should I be setting aside from each payment?

  3. Did I pay a penalty for underpaying, and how do I avoid it?

  4. Is there anything I recorded in a way that made your work harder?

  5. Which retirement account suits my income?

  6. What would you do differently in my position next year?


The last one is open on purpose. A good accountant sees hundreds of businesses like yours and rarely gets asked what she has noticed.


Choosing one


  • Someone who works with businesses like yours. Sole proprietors and small service businesses have their own patterns.

  • Someone who explains. If you leave not understanding your own return, look elsewhere.

  • Clear fees. Ask how she charges before you start.

  • Available outside tax season. The autumn conversation needs someone who answers in October.


What she is not there for


An accountant prepares and advises. She does not keep your daily records unless you hire a bookkeeper for that, and she cannot know about a purchase you did not tell her about. The records are yours. Her skill is in what to do with them.


Three mistakes


  1. Sending everything. More paper is more billable time. Send totals.

  2. Only meeting in spring. By then the year is closed.

  3. Not reading the return. It is the best summary of your business you will be given, and our post on how to read last year's tax return shows the lines that matter.


Start with the whole picture, free


La Soglia, the free membership of the Money Mastery System, holds everything you own and everything you owe in one place, personal and business together, with no bank connection and no card. The income and expense totals for the summary page come from the paid membership, which sorts your transactions and lets you share a report with your accountant.


Bring it to the Collective


What is the best question you ever asked your accountant? The Money Mastery Collective has a discussion feed open on the free membership, and it is a list worth building together.


Questions we hear


What should I send my accountant?

Income by source, expenses by category, estimated tax payments, mileage, home office figures, equipment bought or sold, and contributions to retirement and health accounts.

How can I reduce my accountant's fees?

Send organized totals with a one page summary. Time spent sorting papers and identifying transactions is time you pay for.

When should I talk to my accountant?

Once in the autumn, when there is still time to act before the year ends, and again when the return is ready.

What questions should I ask my accountant?

Ask what share of your profit went to tax, what to set aside, whether you paid a penalty, and what she would do differently in your position.


References


There are no outside figures in this post. The hours and the hourly rate are our own illustration, and fees vary from one practice to another.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. The figures are illustrations, and what your own accountant needs may differ from this list. For guidance on your own circumstances, please speak with a qualified professional who knows them.

There are two months left in the year, and most of what makes tax season easy or hard is decided before December 31. After that date the year is closed, and all that is left is reporting what happened.


None of this is urgent in the way a deadline is urgent. That is exactly why it gets left. So here are twelve things to do while there is still time for them to matter, grouped so you can do a few at a sitting.


Each one takes between ten minutes and an hour. Done across November, they turn January into an ordinary month.


A report ready to share with an accountant in the Money Mastery System

A year that is ready to hand over. Example data.


The short version


  • Bring your records up to date through October now, and keep them current to the end.

  • Check your tax set-aside against the January 15 payment.

  • Date your mileage log. There are two rates for 2026.

  • Decide about retirement and health accounts while the year is still open.


Get the records straight


  1. Close each month through October. Every transaction sorted, every account reconciled. Two months of December work is far easier than twelve.

  2. Total your income by client. Do not wait for forms. For payments made in 2026, a client is only required to send a 1099-NEC at $2,000 or more, so smaller amounts may arrive with no paperwork at all. They are still income.

  3. Date your mileage log. The business rate was 72.5 cents a mile to June 30 and 76 cents from July 1. A single yearly total cannot be split, so the log needs dates.

  4. Collect what you are missing. Receipts for larger purchases, and a W-9 from anyone you paid as a contractor.


Check the tax position


  1. Compare your set-aside with what you will owe. The fourth estimated payment is due January 15 and covers September through December, the longest stretch of the four.

  2. Look at last year's total tax. It is the figure the estimated tax safe harbor is based on, and knowing it tells you the least you need to have paid.

  3. Ask your preparer one question: is there anything I should do before December 31 that I cannot do after?


Line

Example

Profit, September to December

$20,000

Her set-aside rate

25%

Should be set aside for January 15

$5,000

Currently in the tax account

$3,800

Still to move before January

$1,200


The 25% is an example. A gap found in November can be closed from two months of income. The same gap found on January 14 comes out of one.


Decide while the year is open


  1. Retirement accounts. IRA contributions for 2026 can generally be made up to the tax filing deadline, but some plans for the self-employed have to be opened before the year ends. Ask now.

  2. A health savings account, if your health plan qualifies. The 2026 limits are $4,400 for self-only cover and $8,750 for family cover, with $1,000 more from age 55.

  3. Planned purchases. If you were going to buy equipment in January anyway, ask your preparer whether December makes a difference. Never buy something you do not need for the sake of a deduction.


On that last point: spending a dollar to save a quarter in tax still leaves you seventy-five cents poorer. A deduction makes a purchase you needed cheaper. It does not make an unnecessary one free.


Income sorted by source in the Money Mastery System

Income by client, totalled by you and not by the forms that may or may not arrive. Example data.


Set up next year


  1. Review your prices. January is the natural time for a change, and clients need about four weeks of notice, which means deciding in November.

  2. Put next year's dates in your calendar. The four estimated payments, the filing deadline, and a reminder two weeks before each.


Date

What is due

January 15, 2027

Fourth estimated payment for 2026

February 1, 2027

1099-NEC forms to contractors and the IRS

April 15, 2027

2026 return, first 2027 estimated payment, last day for 2026 IRA and HSA contributions

June 15, 2027

Second estimated payment

September 15, 2027

Third estimated payment


Our post on the 2027 tax calendar for the self-employed has every date with what it is for.


If you only do three


Do this

Because

Close the months through October

Everything else depends on knowing your profit

Check the set-aside against January 15

It is the nearest date and the largest payment

Ask your preparer the one question

Some doors close on December 31 and you may not know which


Those three take perhaps two hours between them. They are the difference between a year that ends tidily and one that follows you into spring.


A word about the numbers


Several figures for 2026 changed, some of them partway through the year. We have collected the ones that matter most in 2026 tax numbers for the self-employed, each with its source. Our earlier post on what to do in Q4 so tax season is not a crisis covers the habits behind this list.


End the year knowing where you stand, free


La Soglia, the free membership of the Money Mastery System, holds everything you own and everything you owe in one place, personal and business together, with no bank connection and no card. A net worth figure on December 31 is the best single record of your year, and it takes ten minutes to set up.


Bring it to the Collective


Which of the twelve are you starting with? The Money Mastery Collective has a discussion feed open on the free membership. Say it there, and come back in December to tell us it is done.


Questions we hear


What should a self-employed person do before the end of the year?

Bring records up to date, total income by client, check the tax set-aside against the January 15 payment, and decide about retirement and health account contributions.

When is the last estimated tax payment for 2026 due?

January 15, 2027. It covers income from September through December.

Should I buy equipment before year-end for the deduction?

Only if you needed it anyway. A deduction lowers the cost of a purchase. It does not make an unnecessary one worthwhile.

Do I still report income if I do not receive a 1099?

Yes. Income is reportable whether or not a form is issued, so keep your own total by client.


References


Estimated tax due dates are from the IRS estimated tax questions and answers. The 2026 mileage rates are from the IRS standard mileage rates page. The 1099-NEC threshold is from the Instructions for Forms 1099-MISC and 1099-NEC. The HSA limits are from IRS Revenue Procedure 2025-19, in Internal Revenue Bulletin 2025-21. The set-aside table is our own worked example.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. Tax rules change, vary by state and depend on your whole situation, and deadlines for opening retirement plans differ by plan. For guidance on your own circumstances, please speak with a qualified professional who knows them.

Take what your largest client paid you this year and divide it by your total income. That one figure tells you how much of your business belongs to somebody else's decision.


In the example below the answer is 38%. And because the business has costs that do not shrink when a client leaves, losing her would take 47% of the profit. One email could nearly halve what the owner takes home.


A big client feels like safety. Often it is the largest risk in the business. Here is how to measure it, what the number means, and how to spread the weight without turning good work away.


Income sorted by source in the Money Mastery System

Sorted by client, the largest line is hard to miss. Example data.


The short version


  • Client concentration = your largest client's payments ÷ total income × 100.

  • The hit to profit is bigger than the hit to income, because costs stay.

  • Above about a third from one client, plan for the day she leaves.

  • The fix is not to drop her. It is to grow the rest and keep a larger cushion.


The sum


Client

Paid this year

Share of income

Client A

$36,480

38%

Client B

$19,200

20%

Client C

$14,400

15%

Everyone else

$25,920

27%

Total

$96,000

100%


Three clients provide nearly three quarters of her income, and one of them provides more than a third. If you have never done this sum, the result is usually a surprise.


Why profit falls further than income


Today

If Client A left

Income

$96,000

$59,520

Cost of running the business

$18,000

$18,000

Profit

$78,000

$41,520

Change in profit


down 47%


Income falls by 38% and profit falls by 47%. Her rent, software and insurance are the same with or without Client A, so the whole of the lost income comes out of what she keeps.


This is the mirror image of what a price rise does, and for the same reason. Fixed costs make good news better and bad news worse.


What the number means


Largest client's share

What it suggests

Under 15%

Well spread. One departure is an inconvenience.

15% to 30%

Worth watching. Keep the cushion healthy.

30% to 50%

A real dependence. Plan now for a departure.

Over 50%

Closer to a job than a business, without a job's protections.


These bands are our own way of thinking about it and not a rule. Someone with one long contract and deep savings may be comfortable at 50%. The point is to know your figure and decide on purpose.


How long would it take to replace her?


That is the practical question. If it would take four months to replace Client A's work, you need four months of the gap in hand.


Line

Amount

Profit lost each month without Client A

$3,040

Months to replace the work, estimated

4

Cushion that covers it

$12,160


A cushion sized for an ordinary slow month would not come close. Concentration is a reason to hold more than the usual amount.


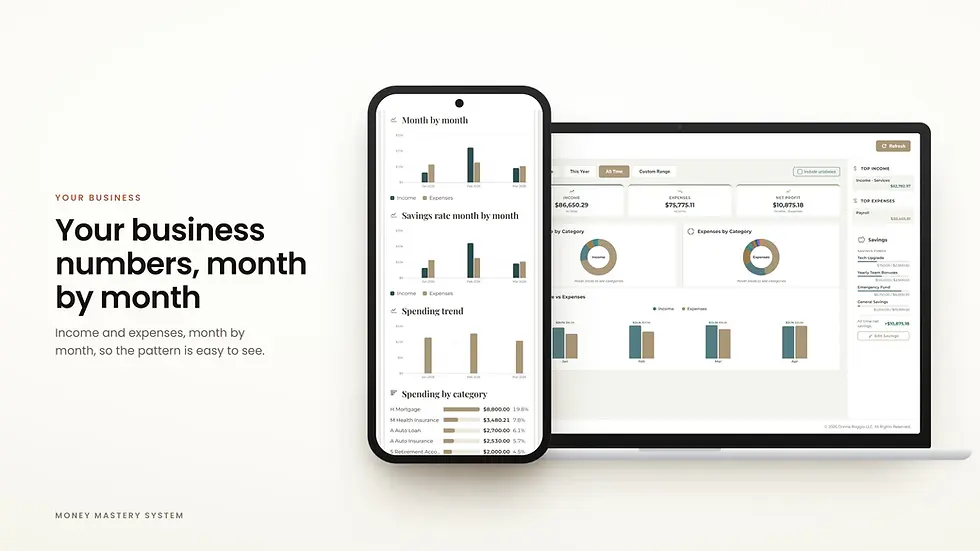
The Money Mastery System business dashboard with income by month

A departure shows up as a step down, not a dip. Example data.


Five ways to spread the weight


  1. Grow the others before you need to. Give Clients B and C a reason to do a little more with you.

  2. Keep finding new clients while you are busy. The time to look is when you do not have to.

  3. Get it in writing. A notice period in the agreement turns a sudden loss into a planned one.

  4. Hold a larger cushion. Sized to the gap and the time to replace it, as in the table above.

  5. Do not let her set your prices. A client who knows she is a third of your income may negotiate as though she owns it.


Notice that none of these is "take on less work from your best client". Good work from a good client is a gift. The aim is to make sure she is one of several legs under the table.


The quiet version of the same risk


Concentration is not only about clients. The same sum works for anything a business leans on.


  • One source of new clients, such as a single referrer or one platform.

  • One service that brings in most of the income.

  • One season that carries the year.

  • One person, which in a business of one is always you.


Run the percentage for each. Where one line is above a third, you have found the thing to protect.


A spread of clients is also one of the things that gives a business value to somebody else, as we set out in what makes a small business sellable.


See it in your own numbers, free


La Soglia, the free membership of the Money Mastery System, holds everything you own and everything you owe in one place, personal and business together, with no bank connection and no card. Income sorted by client, which is where this sum begins, is part of the paid membership.


Bring it to the Collective


What share of your income comes from your largest client? The Money Mastery Collective has a discussion feed open on the free membership. Work it out, and you will not be the only one above a third.


Questions we hear


What is client concentration?

The share of your income that comes from your largest client. Divide what she paid you by your total income and multiply by 100.

How much income from one client is too much?

There is no fixed rule. Above about a third, a single departure would change your year, so it is worth planning for.

Why does losing a client hurt profit more than income?

Because your running costs stay the same. All of the lost income comes out of what you keep.

How do I reduce dependence on one client?

Grow your other clients, keep finding new ones, put a notice period in writing, and hold a cushion sized to the gap.


References


There are no outside figures in this post. Every number is our own worked example.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. The figures and the bands are illustrations, and what level of dependence is acceptable is your own judgment. For guidance on your own circumstances, please speak with a qualified professional who knows them.

bottom of page