top of page

Money Tracking

Income is what comes in. Net worth is what stays. They're measured differently, they change for different reasons, and it's entirely possible to have plenty of the first and almost none of the second.


Most of us were taught to watch income. It's the number on the invoice and the one people ask about. Net worth is quieter, but it's the one that decides whether you can stop working one day.


Here's the difference in plain terms, two business owners with the same income and very different results, and the three numbers that connect one figure to the other.


The Money Mastery System dashboard showing accounts and totals in one view

What has stayed, added up in one place. Example data.


The short version


  • Income is a flow: money coming in over a period of time.

  • Net worth is a snapshot: what you own minus what you owe, on a single day.

  • What links them is how much of your income you keep.

  • If your income rises but your net worth stays flat, the extra is being spent or lost to interest.


A flow and a snapshot


Picture a bathtub. Income is the faucet and spending is the drain. Net worth is the water in the tub. You can have the faucet running hard and still have an empty tub if the drain is open just as wide.


Question

Income

Net worth

What it measures

Money coming in

What you've kept

Measured over

A month or a year

A single day

Goes up when

You earn more

You keep more, pay down debt, or what you own grows

What it tells you

How the business is doing

How you're doing


Two owners, the same income


Both take home $72,000 a year from their businesses for ten years. Neither is careless. They just keep different shares.


Over ten years

The first owner

The second owner

Take-home income

$720,000

$720,000

Share saved each year

3%

18%

Total saved

$21,600

$129,600

Debt paid down

$0

$48,000

Credit card debt added

$14,000

$0

Change in net worth, before any growth

$7,600

$177,600


The same $720,000 passed through both households. One ended ten years later $7,600 better off, and the other $177,600 better off. That's a $170,000 gap. If both owners' savings also grew at an assumed 6% a year, the gap widens to roughly $209,000.


Nothing about their income explains that. Everything about what they kept does.


The three numbers that connect them


  1. Your savings rate. The share of your take-home income that you keep. This is the one you control most directly.

  2. Your debt direction. Whether what you owe is going down or up. Paying off a $4,000 balance raises your net worth by $4,000, just as surely as saving it would.

  3. Growth on what you own. Slow at first, then the biggest of the three over time, which is why time matters so much.


Earning more only helps if at least one of those three moves with it. An extra $10,000 of income with the same habits adds a little. The same $10,000 with a habit of keeping half of it adds $5,000 a year, for as long as you keep it up.


Why business owners are especially prone to this


  1. The business takes the first share. In a growing business, there's always something worth reinvesting in.

  2. Income is easy to see, and net worth isn't. Deposits arrive daily. Net worth has to be added up.

  3. A good year feels like wealth. It's income. It only becomes wealth if some of it stays.

  4. Tax hides in the balance. A healthy account that includes money owed to the IRS makes you look better off than you are.


Personal and business money side by side in the Money Mastery System

Income shows up on the business side. What stays shows up on the personal side. Example data.


How to see your own


You need two net worth figures a year apart, and your income for the year in between.


Line

Example

Net worth a year ago

$142,000

Net worth today

$156,400

Change

$14,400

Take-home income for the year

$72,000

Share of income that became net worth

20%


That last line is the most honest summary of a financial year there is. It includes saving, debt paid off and growth, and a busy month can't flatter it.


If you've never worked out your net worth before, start with our post on what counts toward net worth.


What to do with it


  1. Work out last year's share. It's one division.

  2. Choose one of the three numbers to improve. Usually that's your savings rate, by a point or two.

  3. Take it from each payment, so it happens before the money can be spent.

  4. Check again in three months. A quarter is long enough to see movement and short enough to correct course.


See your own number, free


This is the job La Soglia does. The free membership of the Money Mastery System holds everything you own and everything you owe in one place, personal and business together, with no bank connection and no card, and it shows your net worth changing from one quarter to the next.


Bring it to the Collective


When did you first notice the difference between earning well and keeping well? Share your story in the Money Mastery Collective. The discussion feed is open on the free membership.


Questions we hear


What is the difference between net worth and income?

Income is money coming in over a period of time. Net worth is what you own minus what you owe on a single day, which is what you've kept.

Can you have a high income and a low net worth?

Yes. If most of what comes in is spent or goes to interest, income can be high while net worth stays flat.

How do I turn income into net worth?

Keep a share of each payment, pay down debt, and give what you own time to grow.

Which matters more, income or net worth?

Income shows how the business is doing. Net worth shows whether your own position is improving, so it's the better measure of progress.


References


There are no outside figures in this post. Every number is our own worked example, and the growth figure assumes 6% a year as an illustration.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. The figures are illustrations, and the growth rate is an assumption and not a forecast. For guidance on your own circumstances, please speak with a qualified professional who knows them.

Updated: 1 day ago

Your most popular service might be the one that pays you the least.


Not always, but often enough that it's worth an hour to find out. The service you're best known for is usually the first one you ever priced, back when you knew the least, and it has probably never been revisited.


Popularity and profitability are two different measurements, and only one of them pays you. This post shows how to rank your services by what they really pay per hour, what usually turns up, and what to do about the one at the bottom.


Income sorted by source in the Money Mastery System

Income sorted by where it came from is the starting point. Example data.


The short version


  • Your most-booked service often isn't your best-paid one.

  • Rank each service by what it pays per hour, counting the time around the appointment as well as the appointment itself.

  • Add-ons usually pay the most per hour. The biggest ticket rarely does.

  • For the service at the bottom: raise the price, trim the time it takes, or make it a step toward something better.


What a ranking looks like


Service

Price

Total hours

Pays per hour

Share of bookings

The signature service

$120

2.5

$48

44%

The quick one

$45

0.6

$75

21%

The big one

$400

6.0

$67

9%

The custom one

$250

5.5

$45

12%

The add-on

$35

0.3

$117

14%


Read the first and last rows together. The signature service makes up nearly half of all bookings, and it's the second-lowest rate in the business. The add-on nobody thinks about pays more than twice as much per hour.


This pattern is very common, and almost nobody notices it, because you see your bookings every day but you never see your rate per hour.


How to work out the real rate for one service


Here's the signature service from the table, worked through step by step. Repeat it for each of your services.


  1. The price you actually charge. $120. Not the package price or a discounted price, but what actually lands in your account for this service.

  2. The hours with the client. 2.0 hours. This is the part everyone counts.

  3. The hours around it. 0.5 hours. The consultation, preparation, setup, cleanup, follow-up message, and this service's share of rescheduling and chasing invoices. Track one ordinary week and you'll find this is bigger than you think.

  4. What it costs to deliver. Products, materials, disposables and the card fee. Say $12, or 10% of the price.

  5. The real rate. Take the price, subtract the delivery cost, and divide by the total hours. ($120 − $12) ÷ 2.5 hours = $43 an hour.


The table above shows $48 for this service because it leaves delivery costs out, to keep all five rows simple to compare. With costs included, it's $43.


Then compare that rate with your other services, and only then form an opinion. A rate on its own means very little. Next to the other rates in your own business, it means a lot.


One note: that $43 is before tax and before the hours of your week that no service pays for at all. If you want the figure that actually reaches you, our post on your true hourly rate covers the rest. For ranking your services, though, this number is exactly right, because every service is measured the same way.


Why the hours around the appointment matter so much


The whole exercise depends on counting every hour a service takes, and this is where most people go wrong.


A service that takes two hours in the chair and forty minutes everywhere else is really a 2.7-hour service. Price it as a two-hour service, and you've quietly given away a quarter of your rate.


What usually stands out


  • The signature service is usually near the bottom. It was priced first, when you knew the least, and it's been carried forward out of habit ever since. It's also the hardest one to change, which is why it stays the same.

  • Add-ons are almost always the best rate in the business. A small price, very little time, no setup and no separate booking. Most owners give them away or forget to offer them.

  • The biggest ticket is rarely the best rate. A $400 service that takes six hours pays less per hour than a $45 service that takes thirty-six minutes. Revenue per booking and revenue per hour point in different directions, and only one of them is your life.

  • The gap between best and worst is usually more than double. In the table above, it's $45 to $117. When people expect a small spread and find that, it changes the conversation from pricing to which services they really want to offer.


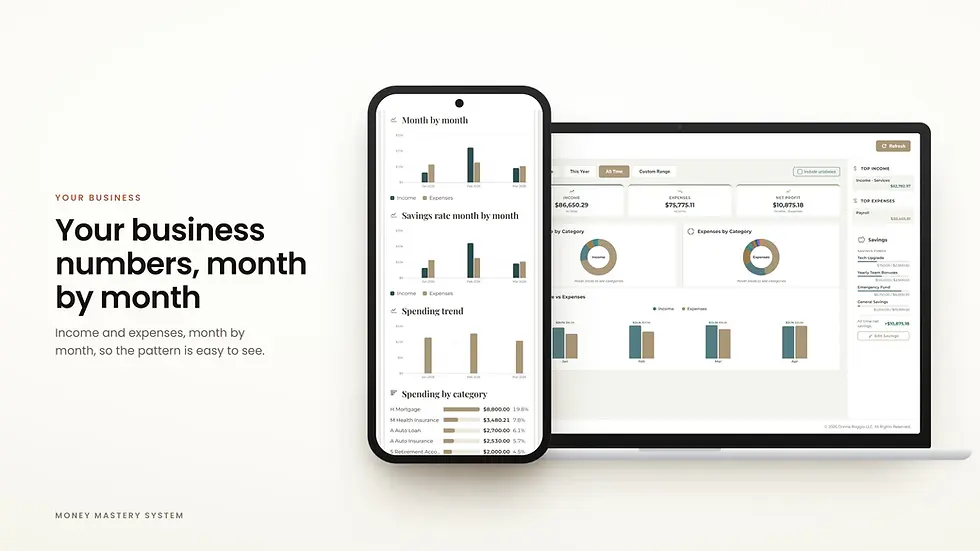
The Money Mastery System business dashboard with income and expenses by month

A business month at a glance. Example data.


What to do with the one at the bottom


There are four options, listed in order of how often they're the right answer.


  1. Raise its price. The most common answer, and the most avoided. If a service is popular and its rate is low, it's underpriced.

  2. Reduce what it takes to deliver. A shorter consultation, a tighter scope, fewer unpaid revisions.

  3. Make it a step rather than a destination. A low-rate service that reliably leads clients to a higher-rate one is doing a different job, and it should be judged on what comes after it.

  4. Stop offering it. This is the rarest answer, and occasionally the only honest one.


What you shouldn't do is keep it unchanged just because it's what you're known for. Being known for your lowest-paid work is a slow problem.


Five easy mistakes when ranking services


  1. Counting only the hours with the client. The hours around the appointment are where the ranking is decided, and leaving them out flatters exactly the services that need the closest look.

  2. Using your list price instead of the average price you actually got. Discounts, packages and friend rates all belong in the number you divide.

  3. Ranking by total revenue. That only tells you what's popular. Popular and profitable are different things, and that difference is what this whole post is about.

  4. Leaving out the services you no longer want to do. Resentment isn't data, but it's often pointing at some. Rank those too and find out.

  5. Doing it once and never again. Supplier prices change, you get faster, and a service that ranked third two years ago might rank last now.


Where the numbers come from


You need two things: your income split by service, and an honest count of the hours around each one.


Counting the hours takes one week of paying attention, and nobody can do that for you. Splitting your income by service is a sorting job. That's what Rise, at $49.99 a month, does: it sorts your income by service and keeps it sorted, because Clarity remembers how you labeled things last time. Its income-by-service report is this post's table, built from your own bookings.


La Soglia, the free membership, holds everything you own and everything you owe, with no bank connection and no card. That's useful too, but for this particular job, the paid membership is the one that does it.


Bring it to the Collective


The bottom row of your table can be hard to look at alone, and almost everyone has one. Share yours in the Money Mastery Collective. The discussion feed is open on the free membership.


Questions we hear


What if a low-rate service brings in new clients?

Then it's marketing, and it should be measured as marketing. Track how many of those clients come back for something else. If they don't, it isn't a way in, it's just a discount.

Should I count my own time if I am the business?

Yes, especially then. Unpaid owner time is how a business can look profitable while the owner isn't really being paid.

How often should I redo this?

Once a year is plenty. October is a good month for it, because you still have time to change prices before January.

How do I know which of my services is most profitable?

Divide what each service brings in, after its delivery costs, by every hour it takes, including preparation and follow-up. Then compare the results side by side.


References


There are no outside figures in this post. Every number is our own worked example.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. The table is a worked example, not a typical business. For guidance on your own circumstances, please speak with a qualified professional who knows them.

Yes, your car belongs in your net worth. It's something you own, so it goes on the asset side at what it would sell for today. If there's a loan on it, the loan goes on the debt side.


The harder question is what else to count. Jewelry, furniture, a camera, the equipment in your studio: all of it cost real money, and almost none of it is worth what you paid.


Here's a simple test for deciding what goes on the list, and how to put an honest figure on nine common things you might own.


The Money Mastery System dashboard showing accounts and totals in one view

Every line at what it would sell for, not what it cost. Example data.


The short version


  • Count something if you could sell it for a meaningful amount and you'd notice it gone.

  • Use what it would sell for today, never what you paid.

  • List any loan against it separately, as a debt.

  • Leave out everyday household things. They add noise, not information.


A simple test for what to count


If you're unsure about something, ask yourself two questions.


  1. Could I sell this within a month for $1,000 or more?

  2. Is there a real market for it, with prices I can look up?


If the answer to both is yes, it goes on the list. Anything else is part of your life, and it doesn't need to be part of your net worth. The $1,000 line is only a suggestion. Pick your own number and keep it the same every time.


Nine things, and how to value each one


What you own

Count it?

How to value it

1. Your car

Yes

A private-sale price from a used car guide, for your mileage and condition

2. A second vehicle, boat or trailer

Yes

The same way, and lean on the low side

3. Fine jewelry and watches

If they're significant

What a dealer would pay you, which is well below an insurance appraisal

4. Business equipment

Yes, on the business side

What it would sell for used, not what it cost and not its tax value

5. Art and collectibles

Only if there's a real market

Recent sale prices of the same or similar pieces

6. Furniture and appliances

Usually not

They resell for a small fraction of what they cost

7. Clothes and handbags

Usually not

Unless a specific piece has a known resale price

8. Electronics

Usually not

They lose value fast

9. Money you're owed

Yes

What you realistically expect to collect


The car, worked through


Line

Amount

What she paid three years ago

$28,000

What it would sell for today

$17,500

What she still owes on the loan

$14,200

What the car adds to her net worth

$3,300


The car goes on the asset side at $17,500, and the loan goes on the debt side at $14,200. The $28,000 she paid doesn't appear anywhere. It's history.


Notice how small the result is. A car that feels like a $28,000 asset adds just $3,300 to her net worth. That's not a reason to leave it off. It's exactly why you should put it on, because it corrects a picture that was too generous.


If you owe more than the car is worth


Both lines still go in, and the car lowers your net worth. A car worth $15,000 with $18,000 owed on it counts as minus $3,000. That's uncomfortable, but it's accurate, and it improves every month you make a payment.


Why insurance values can mislead you


An insurance appraisal tells you what it would cost to replace something at retail. What you could actually sell it for is a different, much lower number. For net worth, the selling price is the right one, because net worth asks what you have, not what it would cost to buy it again.


Personal and business money side by side in the Money Mastery System

Business equipment sits on the business side, at what it would sell for used. Example data.


Business equipment is a special case


A stylist's chairs, a photographer's cameras and a baker's oven all have real value. But three different numbers can be attached to each one, and only one of them belongs here.


Number

What it means

Use it for net worth?

Cost

What you paid

No

Tax value

What you paid, minus the depreciation you've claimed

No

Resale value

What a buyer would pay for it used

Yes


Equipment you've fully written off for tax can still be worth thousands to a buyer. And equipment you bought last month may already be worth a third less.


How often to update the values


Once a year is plenty for things you own. Cars and equipment lose value slowly and steadily, so updating them every quarter adds work without telling you much. Update loan balances every quarter, though, because they change with every payment.


Three common mistakes


  1. Using what you paid. It's the most common mistake, and it always makes the picture look better than it is.

  2. Counting everything in the house. A long list of small guesses makes the total less reliable, not more.

  3. Forgetting the loan. An asset without its debt is only half the story.


Put the lines in, free


This is what the Net Worth Tracker is for. La Soglia, the free membership of the Money Mastery System, holds your car, its loan, your home, your business and everything else you own and owe in one place, with no bank connection and no card. For the full list of what belongs on each side, see what counts toward net worth. For the biggest line of all, see how to count a house and a mortgage.


Bring it to the Collective


Not sure whether something belongs on your list? Ask in the Money Mastery Collective. The discussion feed is open on the free membership.


Questions we hear


Is a car an asset in net worth?

Yes. List it at what it would sell for today, and list any loan on it separately as a debt.

Do I include furniture in my net worth?

Usually not. Furniture and everyday household things resell for a small fraction of their cost and add little to the picture.

How do I value jewelry for net worth?

Use what a dealer would pay you, not an insurance appraisal, which reflects the cost of replacing it at retail.

How do I value business equipment?

At what it would sell for used. What it cost and its value for tax purposes are different figures.


References


There are no outside figures in this post. Every number is our own worked example.


Start free with La Soglia


La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.


Keep in touch


Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.


A note on what this is


This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. The figures are illustrations, and what something would sell for depends on its condition and market. For guidance on your own circumstances, please speak with a qualified professional who knows them.

bottom of page