top of page

A steady weekly money routine for women business owners is one of the most freeing habits you will ever build. Fifteen focused minutes on the weekend can make Monday feel bright, informed, and calm. That is not a stretch. It is what happens when your numbers have a regular home.
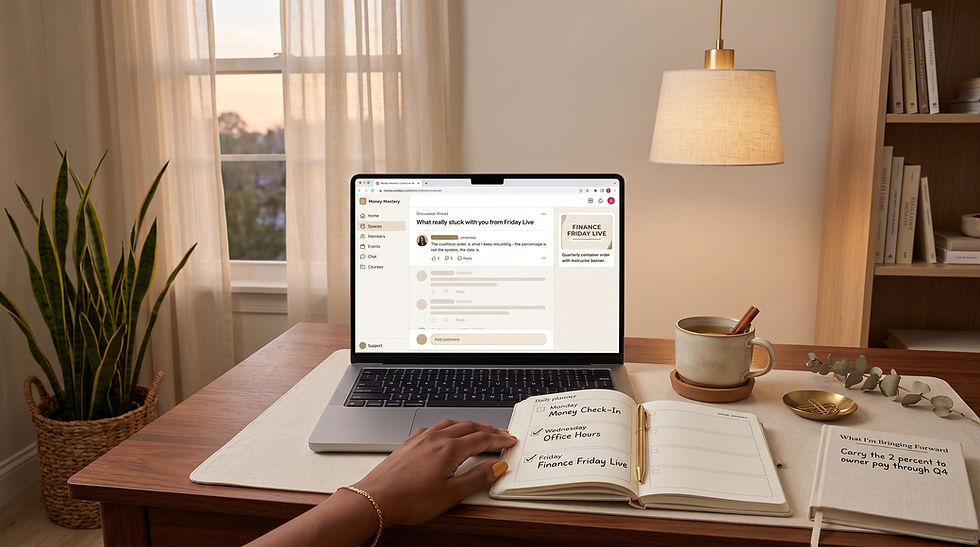

Hand on laptop in cozy home office; planner shows Money Check-In, Office Hours, and Finance Friday Live.

Ready to make weekends feel lighter, not busier? Here is the exact reset.


The 15-minute weekly money routine for women business owners at a glance


  • Minutes 1-5: Look back at last week

  • Minutes 6-10: Look ahead at next week

  • Minutes 11-15: Move money and make one decision


That is it. Small, powerful, repeatable.


Minutes 1-5: what to review from last week

  1. Money in

  2. Money out

  3. One unfamiliar or surprising charge

  4. One transfer you meant to make


Minutes 6-10: what to see about next week

  1. Bills coming due

  2. Tax transfer to schedule

  3. Savings or reserve moves

  4. Owner pay plan


Minutes 11-15: one decision that makes next week easier

  1. Move money to the right account

  2. Cancel or renegotiate one charge

  3. Follow up on an invoice

  4. Schedule your Finance Friday Live attendance


Why this routine feels so good

  • It replaces vague dread with clear structure.

  • It replaces catch-up with consistency.

  • It replaces guessing with knowing.


Fifteen minutes on Sunday can lift the entire week that follows.


Use this simple table every weekend

Review area

Question to ask

Income

Did what I expected land?

Expenses

Was anything a surprise?

Upcoming bills

Anything I need to prepare cash for?

Tax and savings

Do I need to move money?

Owner pay

Is my rhythm still working?

One decision

What one move will improve next week?

How the Money Mastery System makes it easier


Laptop and tablet show financial charts beside a Spending Audit notebook, coffee mug, and pen on a tidy desk.

Inside the Money Mastery System system, this fifteen-minute routine becomes smooth because:

  • Your income and expenses live in one place

  • Your monthly breakdown updates as you go

  • You can see what you kept without hunting through statements

  • You can review categories at a glance


Then inside the Collective, the community keeps you accountable:

  • The daily blog gives a small nudge back into your numbers

  • The discussion feed helps you share and hear how others are doing the same work

  • Finance Friday Live gives you weekly teaching from Donna

  • The Money Reset Call helps close each month cleanly


Inside the Collective, the Money Mastery System system helps you see what you kept last month on one screen, alongside other women doing the same work. That is why the routine sticks.


An uplifting story of one Sunday reset

Picture Layla, a coach and salon business owner. She sits down at her kitchen table on Sunday morning with tea and her laptop. She opens the Money Mastery System system, glances at last week's income and expenses, spots one subscription she does not need, marks the Wednesday tax transfer she wants to make, and pays herself for the week. Fifteen minutes. Two decisions. One weekend calm.


Monday morning arrives, and Layla starts the week from a settled place instead of a scattered one. That is the difference this rhythm makes.


Bonus: a first-week starter plan

If this is new to you, use this three-week onboarding:

  1. Week 1: Do the fifteen-minute reset. Do not aim for perfect. Aim for done.

  2. Week 2: Add the tax transfer step and the one-decision step.

  3. Week 3: Attend Finance Friday Live to reinforce what you are seeing.


By week four, this becomes part of who you are.


Cozy desk with laptop showing Money Mastery, planner and notes open, coffee mug, plants, and a calm home office setup.

What to do next

Choose your weekend time, open your Money Mastery System system, and step into the Collective at https://moneymasterycollective.circle.so.


FAQ


Why is a weekly routine more effective than an occasional deep dive?

Occasional deep dives feel productive in the moment, but the gap between them is where money slowly gets away from women. A weekly rhythm keeps everything current, small, and manageable. Instead of trying to reconstruct three months of context every once in a while, a fifteen-minute weekend reset means the story is always fresh in your mind and current in the Money Mastery System system. Consistency also protects your nervous system. You never have to face a giant pile of catch-up, which means you never have to talk yourself into starting. The work becomes a low-effort habit that supports every decision you make during the week that follows.


What if my income and schedule are unpredictable?

Unpredictable income and schedules are exactly why a weekly rhythm matters even more. When cash flow moves around, having a steady reset gives you a place to notice patterns, protect your tax set-asides, and adjust owner pay before the month is over. If you cannot commit to the same day every week, choose a two-day window instead, such as Saturday or Sunday morning. If you miss a weekend, do it Monday morning. The point is not perfection. The point is that the numbers never go longer than about a week without your attention, which is what keeps them workable.


How does this routine connect to bigger goals like retirement and savings?

The weekly reset is the on-ramp to every big financial goal a woman can set for herself. Retirement, savings, buying a home, expanding the business, and building a legacy all require consistent small choices, not occasional huge ones. When you know each week that your tax money is protected, your savings is growing, and your owner pay is happening, you build the trust with yourself that bigger decisions require. Over the course of a year, fifty-two of these small weekly resets add up to a completely different financial life. That is the compounding effect of rhythm, and it is exactly what the Money Mastery System system + the Collective are designed to support.

Learning how to figure out what you kept last month in your business matters because revenue is not the same thing as relief.


Hand sorts receipt stack beside notebook titled What I Kept on wooden table with tea, oranges, and pouch; calm, tidy workspace.

You can have a month that looks strong from the outside and still feel financially squeezed on the inside. You can hit a good revenue number and still not know whether the business is actually supporting your life. You can feel busy, productive, and booked while still being unclear about whether the money is truly landing where it needs to.


That gap is where a lot of unnecessary stress lives.


The Federal Reserve’s 2025 Small Business Credit Survey makes the environment clear: 75% of small businesses cited rising costs as a financial challenge, 56% said paying operating expenses was a challenge, and 51% said uneven cash flow was a challenge. Federal Reserve Small Business Credit Survey In a climate like that, top-line revenue tells only part of the story.


What you kept tells the more honest part.


How to figure out what you kept last month in your business starts with the right question


Most business owners start by asking, “What did I make?”


That is not a useless question. It is just incomplete.


The more useful question is: after the business needed what it needed, what was actually left?


That means looking beyond deposits. It means looking beyond the excitement of a busy month. It means separating the story of revenue from the story of expenses, tax obligations, owner pay, and real cash availability.


If you have already read What Is a Profit and Loss Statement?, this will feel familiar. A P&L helps you see how much the business earned, how much it spent, and whether it came out ahead. But for day-to-day clarity, many owners also need a simpler translation: what was truly left at the end of the month?


That translation matters because it is the number that tends to shape your next decision.


If what you kept is lower than you expected, you may need to look at pricing, recurring expenses, owner pay, or tax set-asides.


If what you kept is healthier than you expected, you may have more flexibility than your nervous system is telling you.


How to figure out what you kept last month in your business gets easier when you stop mixing profit and cash flow


This is where many business owners get tripped up.


Profit and cash are related, but they are not identical.


Your business can look profitable on paper and still feel tight in the account because timing matters. Client payments arrive late. Expenses hit early. Taxes are due at awkward moments. A debt payment or a software renewal can distort how a month feels if you are only watching the bank balance.


That is why What Is Cash Flow? (And Why It’s Not the Same as Profit) is such a helpful companion read. Cash flow tells you about movement. The number you kept helps you judge what was really available after the month did what it did.


A simple way to calculate it without making it harder than it needs to be

Person taps a tablet showing a Money Mastery Financial Dashboard with charts on a cozy desk beside coffee, notebook, and plant.

You do not need a perfect accounting close to do this well.


You need a repeatable monthly process.


Start with the money that came in from real business activity.


Then total the money that went out for real business expenses.


Keep personal withdrawals or owner transfers visible instead of letting them disappear into the background.


If part of what remains really belongs to taxes, savings, or a known upcoming obligation, count that honestly too.


The point is not to create a perfectly formal accounting document inside the blog post.


The point is to help you see the month more truthfully.


When you make this a monthly habit, patterns become easier to see:

  • revenue may be climbing while retained money stays flat

  • owner pay may be irregular even in strong sales months

  • one category may be quietly absorbing growth

  • the month may feel “good” emotionally but weak financially


Those are the kinds of insights that change behavior.


Why this number matters more than most owners expect


Knowing what you kept does three useful things.


First, it calms vague money anxiety.


Vagueness is exhausting. When you do not know what is true, every decision feels heavier. Once you know what was actually left, you stop solving made-up problems and start solving real ones.


Second, it helps you pay yourself more honestly.


The IRS is very clear that how you compensate yourself depends on your business structure. IRS guidance on paying yourself Even before you get into structure-specific mechanics, you still need a realistic sense of what the business is producing. If you do not know what is being retained, owner pay easily becomes reactive instead of intentional.


Hands calculating monthly income and expenses on a Casio calculator beside a notebook, coffee, and plant on a sunny wooden desk.

That is also why How to Pay Yourself as a Business Owner belongs in this conversation. Business owners who do not know what they kept usually either underpay themselves, overdraw in random bursts, or avoid the subject altogether.

Third, it helps you make better growth decisions.


When what you kept is clear, it becomes easier to tell whether a pricing change is overdue, whether a recurring cost is justified, whether the current offer mix is strong enough, or whether the business is just creating more work without enough financial return.


A real example most business owners will recognize

Picture a solo service provider named Mia.


She had a busy month. She knows money came in. If someone asked how business was, she would probably say, “Good, but I still feel behind.”

That sentence tells you almost everything.


When Mia actually reviews the month, she sees that deposits were strong, but supplies were higher than usual, a few subscriptions had crept up, and she had transferred money to herself whenever life got tight without any set rhythm. She also never mentally protected the portion that still needed to go toward taxes.

Before the review, the month felt emotionally confusing.


After the review, it becomes specific.


She can see that the issue is not that the business made “bad money.” The issue is that the month did not leave enough after all the hidden drains were accounted for.


That kind of clarity is not small. It changes what she does next.


Why this matters even more in a second chapter

For the Money Mastery audience, this conversation is even more important because many readers are doing more than just running the business. They are also trying to stabilize a household, think about retirement, build savings, and make the next decade more secure than the last one.


The Federal Reserve found that in 2024, 55% of adults had rainy-day savings that could cover three months of expenses, and among adults 45 to 59, the figure was 54%. Federal Reserve savings and investments data That means a lot of midlife adults are still navigating with limited buffer.


When that is true, understanding what your business actually kept stops being an abstract finance exercise. It becomes part of how you protect your future.

If you want help seeing your numbers in a more honest, useful way, the next step is simple: take the Money Clarity Quiz.


FAQ

Is what I kept the same as profit?

Not always in the way owners use those words day to day. The goal here is practical clarity around what was truly left after the business needed what it needed.


Why can a good revenue month still feel tight?

Because deposits alone do not show expenses, timing issues, tax obligations, or inconsistent owner pay.


What should I do if I realize I am keeping less than I thought?

Start by reviewing pricing, top expense categories, owner pay habits, and whether money is being set aside properly for taxes and savings.

bottom of page