


Updated: 1 day ago
A monthly financial review is a short check of four things: what came in, what went out, what you kept, and what you owe. Each month, look at your profit and loss, your cash in every account, unpaid invoices, recurring charges and your tax set-aside, then compare them to last month. Here is the checklist.
Most people don't skip their monthly review because they don't care. They skip it because they don't have a clear, repeatable process. They sit down, open the bank account, feel a wave of dread, and close the laptop. That's not a character problem. That's a process problem.
The 10-step monthly financial review checklist
Do these in order, once a month, in the first few days after the month ends.
Gather four things: your bank and card statements (business and personal), your profit and loss report or spreadsheet, your list of unpaid invoices, and last month's review notes.
Write down total income for the month, by source. Service revenue, product sales, any other stream. Flag anything you expected that didn't arrive.
Write down total expenses, by category. Look at your top five categories, not every transaction.
Work out what you kept: income minus expenses. That is your net profit for the month.
Compare to last month and the same month last year. Note anything that moved by more than about 10%, up or down, and why.
Check your recurring charges. Any new ones? Any that went up? Any you no longer use?
Check cash in every account: operating, tax savings, profit or emergency savings, personal.
Check your tax set-aside. Did the right percentage of this month's income move into your tax account?
List who owes you money and what you owe: unpaid invoices, card balances, loans, bills due this month.
Answer five questions and write down one action for next month (see below), then book next month's review in your calendar.
How to do it in about 15 minutes: three five-minute blocks
The ten steps fit into three short blocks once your numbers are in one place. The first few times will take longer while you work out where each number lives. That's normal.
Minutes 1–5: what came in (steps 1–2). Total income by source. Keep business revenue apart from anything personal, like a partner's paycheck or a side gig, so you see each stream clearly instead of one combined number. This is much easier if you already keep business and personal money separate.
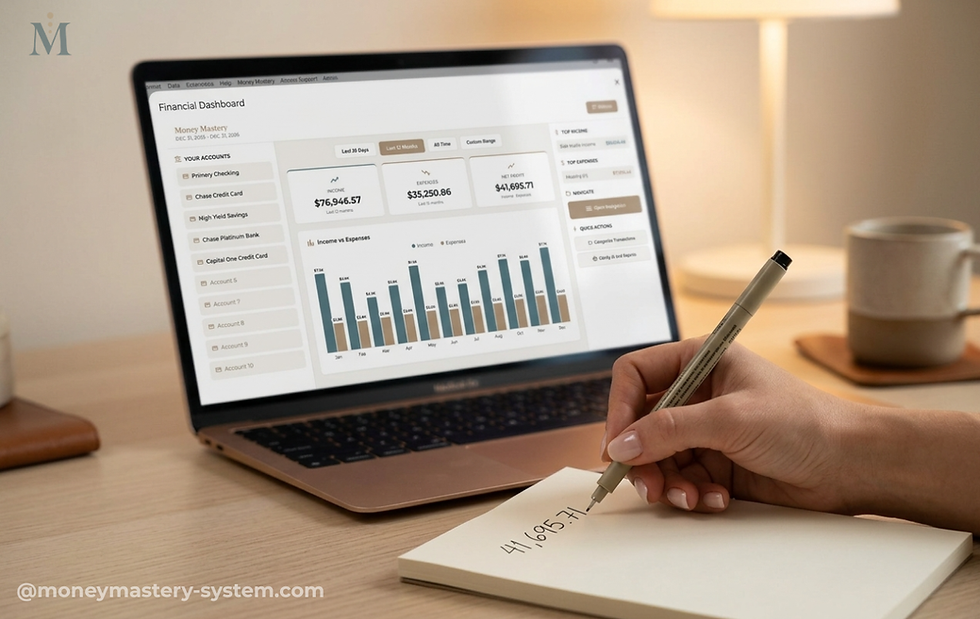
Minutes 5–10: what went out (steps 3 and 6). Categories, not transactions. The transaction-by-transaction work belongs in a weekly check-in. Look at business spending first, then personal, so the two don't blur together.
Minutes 10–15: where you stand (steps 4–5 and 7–10). Net profit, cash, tax set-aside, what you owe. Estimates and round numbers are fine. What matters is that you look every month, so you spot a trend before it becomes a crisis.
What financial reports should I review every month?
For a small service business, five reports cover it: your profit and loss (what you earned, spent and kept), your cash balance in every account, your unpaid invoices (who owes you), a recurring charges list, and your tax set-aside balance. Once a month, also update a quick net worth snapshot so business progress shows up in your personal picture.
You don't need accounting software to produce these. A spreadsheet works. Here is what each one tells you:
Profit and loss (P&L): whether the month made money. If you've never read one, start with how to read a profit and loss statement. If you don't have one yet, you can set up a simple P&L in Google Sheets in an afternoon.
Cash balances: profit and cash are not the same thing. A good month on paper can still leave the bank account thin if clients haven't paid.
Unpaid invoices: money you've earned but don't have yet.
Recurring charges: the quiet leaks (more on these below).
Tax set-aside: whether you're keeping up, or building a surprise for April.
What should a monthly revenue report include?
A useful monthly revenue report for a small business fits on one page: total revenue, revenue by service or income stream, number of clients or appointments, average sale per client, the comparison to last month and the same month last year, and money invoiced but not yet collected. Those six lines show whether you're growing and where it's coming from.
If you have more than one income stream, keep each one on its own line. Combined totals hide which part of the business is doing the work. Tracking multiple income streams in one place walks through the setup. And remember that revenue is only the top line. A month with record revenue and rising costs can leave you with less, which is why step 4 (what you kept) comes right after it. Revenue vs profit explains the difference in plain terms.
How do I review my recurring expenses at the start of each month?
Keep one list of every recurring charge, with its amount, billing date and how often it bills (monthly or annual). At the start of each month, compare last month's statements against that list, line by line. Look for three things: new charges, charges that went up, and anything you no longer use. Cancel or question it that day.
The hard part is building the list the first time. The best way to track recurring bills has the full tracker, including how to catch subscriptions that bill once a year. Your monthly review is simply the day you check it.
What to compare each month
One month of numbers on its own doesn't tell you much. The comparisons do.
Income vs last month, and vs the same month last year if your business is seasonal.
Total expenses vs last month. A jump isn't automatically a problem, but an unexplained jump is worth five minutes. Maybe it was a one-time purchase. Maybe a recurring charge went up without notice.
Net profit over the last three months. One low month can be a fluke. Three falling months in a row is a trend.
Savings and tax set-aside vs your goal. If you planned $500 and saved $200, that's information, not a failure. Adjust the goal or the plan.
If you sort spending into needs and wants, this is also the moment to check the split. Needs vs wants budgeting shows how.
Five questions to ask before you close the laptop
Numbers are only useful once you interpret them. Run through these after the ten steps.
Did anything surprise me? A charge, a category that spiked, income that came in higher than expected. Notice it.
Does my spending match my priorities? If it doesn't, that's not a moral failing. It's next month's adjustment.
What will I change next month? Cancel a subscription, raise your tax set-aside, follow up on a price you haven't raised in a while. Pick one.
What do I need to follow up on? Unpaid invoices, charges to dispute, renewals coming up. Write them down.
How do I feel about my money right now? Anxious and confident are both information. Over time this answer tends to change as the numbers get familiar.

Weekly vs monthly review: what's the difference?
A weekly check-in is for transactions: categorize new charges, catch anything odd, and make sure who-owes-you is current. It takes about 10 minutes and keeps the data clean. The monthly review is for totals and trends: what you kept, how it compares, what to change. Weekly keeps the records tidy. Monthly turns them into decisions.
If reviewing your spending once a week feels like too much, keep it short: open your accounts, categorize anything new, and stop. The weekly money reset is a ready-made version.
Start with this month
You don't need to wait for the first of the month. Run the ten steps today with whatever numbers you have so far. A partial review still builds the habit. Then put a recurring appointment in your calendar for the second or third day of every month and call it "Monthly Money Review." If you ever miss a month, don't try to catch up on two at once. Just do the current month and keep going.
Want company while you build the habit? The Money Mastery System gives you five connected workbooks, Clarity AI, and the Money Mastery Collective, a community of people doing the same work beside you. Start free with La Soglia.

If you would rather run the month by allocation than by review, the Profit First method, explained, splits income into accounts before you spend it.
In December, swap this month's review for the year-end money checklist for the self-employed.
Frequently asked questions
How long should a monthly financial review take?
About 15 minutes once your accounts and reports are in one place. The first two or three reviews usually take longer while you work out where each number lives. If it regularly takes more than half an hour, the problem is usually scattered records, not the review itself.
When is the best time to do a monthly financial review?
In the first few days of the new month, after the last month's transactions have cleared and your statements have closed. The exact day matters less than doing it on the same day every month. Put it in your calendar as a recurring appointment.
What financial reports should a small business owner review every month?
Your profit and loss, the cash balance in every account, unpaid invoices, your list of recurring charges, and your tax set-aside balance. A quick monthly net worth check is a useful sixth if you want to see business progress in your personal picture.
Is a monthly financial review the same as closing the books?
No. Closing the books is the bookkeeping job of making sure every transaction is categorized and reconciled. The review is what you do afterward: you look at the finished numbers and decide what to change. If you do your own books, close first, then review. What to do before you close out your business month covers the closing side.
Can I do a monthly financial review for free?
Yes. Your bank statements, a spreadsheet or notebook, and the checklist above are all you need. Free bank exports and a simple Google Sheet will cover every step.