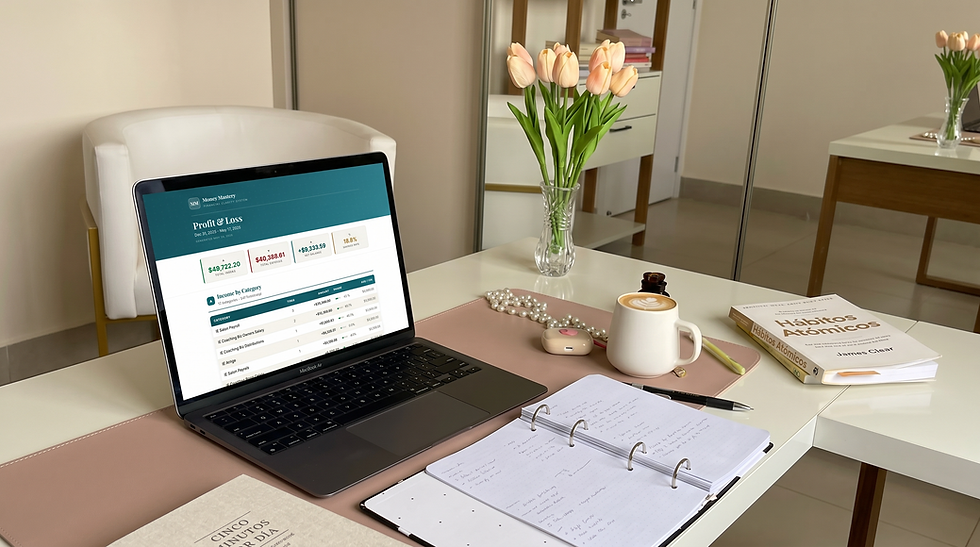
Learning how to read a profit and loss statement, or P&L, comes down to four numbers: what came in, what it cost you to deliver, what it cost you to keep the doors open, and what was left. Everything else on the page is detail underneath those four. This guide walks through each section in plain language, shows you what a real statement looks like line by line, and tells you what to look at first, so the next time a P&L lands in your inbox you can actually read it instead of filing it away.
This post changes that. We're going to walk through every section of a profit and loss statement, explain what each part means in plain terms, and show you how to use the information it gives you. No accounting degree required. No financial advice given. Just education that helps you understand the document that tells the most honest story about how your business is performing.
What Is a Profit and Loss Statement?
A profit and loss statement, also called a P&L or an income statement, is a financial document that shows how much money your business earned, how much it spent, and whether you came out ahead or behind over a specific period of time. That period is usually a month, a quarter, or a year.
Think of it as a scorecard for your business. Revenue goes at the top. Expenses go in the middle. And the bottom line tells you whether your business made money or lost money during that period.
The P&L doesn't tell you how much cash is in your bank account right now.
That's a common misconception. Your bank balance is affected by things like loan payments, owner's draws, and transfers that don't show up on a P&L. What the P&L does tell you is whether your business operations are generating profit. Those are two very different things, and understanding the distinction is one of the most important things you'll take from this post.
Every business, regardless of size, should have a P&L that gets reviewed regularly. If you've been doing your monthly financial review, the P&L is one of the most valuable documents to include in that process.
The Four Sections of Every P&L Statement Explained
Every profit and loss statement, whether it's a one-page document from a solopreneur or a 20-page report from a larger company, follows the same basic structure. There are four sections, and once you understand what each one represents, the entire document starts making sense.
Section One: Revenue (Also Called Income or Sales)
This is the top of your P&L. Revenue is the total amount of money your business earned during the period. If you sell products, this is total sales. If you sell services, this is total fees or payments received from clients. If you have multiple revenue streams, they'll each be listed here as separate line items.
For example, a freelance web designer might have three revenue lines: website design projects ($8,500), monthly maintenance retainers ($2,400), and a digital course she sells ($1,200). Her total revenue for the month is $12,100.
The revenue section tells you how much money your business brought in before any expenses are subtracted. It's your starting point.
One thing to watch for here: revenue isn't the same as collections. If you invoiced a client in March but they paid in April, the revenue might show up in March on an accrual-based P&L or in April on a cash-based P&L. Most small business owners use cash-based accounting, which means revenue shows up when the money actually hits your account. If you're not sure which method your P&L uses, that's a good question to ask your accountant.
Section Two: Cost of Goods Sold (COGS)
This section appears on P&L statements for businesses that sell physical products or have direct costs tied to delivering their service. Cost of goods sold includes the expenses directly connected to creating or delivering what you sell.
For a bakery, COGS would include flour, sugar, butter, packaging, and the hourly wages of the baker. For a consultant, COGS might include subcontractor fees or specialized software used exclusively for client deliverables. For a retail shop, it's the wholesale cost of the products on the shelves.
Not every business has a COGS section. Many service-based businesses skip it entirely because their costs aren't directly tied to individual sales. If your P&L doesn't have this section, that's fine. It just means your business model doesn't require it.
When you subtract COGS from revenue, you get gross profit. This number tells you how much money you made from your core business activity before accounting for all the other costs of running the business.
Section Three: Operating Expenses
This is usually the longest section on a P&L, and it's where most of the actionable insights live. Operating expenses are all the costs of running your business that aren't directly tied to creating your product or delivering your service.
Common operating expense categories include rent or office space, utilities, software subscriptions, marketing and advertising, insurance, professional services like legal or accounting fees, office supplies, travel, meals, phone and internet, bank fees, and payroll if you have employees.
Each of these categories appears as a line item with a dollar amount. The more specific your categories, the more useful this section becomes. A P&L that lumps everything into "General Expenses" tells you almost nothing. A P&L that breaks things into 15 or 20 distinct categories tells you exactly where your money is going.
This is where the detailed expense categories you set up in your tracking system pay off. If you're categorizing your spending with specificity throughout the month, your P&L automatically reflects that detail. Systems like Money Mastery use over 400 expense categories, which means the P&L it generates gives you a level of clarity that broad-category systems simply can't match.
Section Four: Net Profit (or Net Loss)
This is the bottom line. Literally. Net profit is what remains after you subtract all expenses (COGS plus operating expenses) from your total revenue.
If the number is positive, your business made money during that period. If it's negative, your business spent more than it earned. Both outcomes are useful information. A positive net profit tells you the business is generating surplus. A negative net profit tells you something needs to change, whether that's increasing revenue, reducing expenses, or both.
Net profit is the single most important number on your P&L. It's the answer to the question every business owner should be asking: after everything is accounted for, did my business come out ahead this month?
Here's a simple example of a complete P&L for a small service-based business:
Revenue: $14,000 Cost of Goods Sold: $1,200 (subcontractor) Gross Profit: $12,800 Operating Expenses: $7,400 Net Profit: $5,400
That business owner earned $14,000, spent $8,600 total, and kept $5,400. The P&L makes that story visible in less than five lines.
Download the free Money Mastery Net Worth Tracker at https://moneymastery-system.com/free. It puts your personal and business accounts side by side across sixty account types and twelve tabs, and it stays yours.
How to Read a Profit and Loss Statement: What to Look for First
Now that you understand the structure, let's talk about what to actually do when you sit down with your P&L. You don't need to analyze every line item every time. Here's where to focus your attention.
Look at Revenue First
Is your revenue growing, shrinking, or flat compared to last month? Compared to the same month last year? If you have multiple revenue streams, which ones are performing and which ones are lagging? Revenue trends over three to six months tell you whether your business is heading in the right direction.
Look at Your Largest Expense Categories
Don't start with the small stuff. Find your three to five biggest expense categories and look at them first. These are the line items that have the most impact on your bottom line. If one of them jumped significantly from last month, that's worth investigating. It might be a one-time cost, or it might be the start of a pattern.
Look at Your Net Profit Margin
Your net profit margin is your net profit divided by your total revenue, expressed as a percentage. If you earned $14,000 and kept $5,400, your net profit margin is about 38.6%. This percentage matters more than the raw dollar amount because it tells you how efficient your business is. A business earning $50,000/month with a 5% margin is keeping less than a business earning $15,000/month with a 40% margin.
Track your profit margin over time. If it's shrinking while your revenue is growing, that means your expenses are growing faster than your income. That's a trend worth catching early.
Common P&L Mistakes Small Business Owners Make
Understanding the structure of a P&L is one thing. Reading it accurately is another. Here are the most common mistakes that lead to confusion.
Confusing Revenue with Profit
This one trips up a lot of people. Just because you had a $20,000 month doesn't mean you made $20,000. Revenue is the top line. Profit is the bottom line. Everything in between is what the business costs to operate. A $20,000 revenue month with $18,000 in expenses is a $2,000 profit month. Knowing the difference prevents you from making spending decisions based on your income instead of your actual profit.
Not Reviewing the P&L Monthly
A P&L is most useful when it's current. Looking at it once a year during tax prep is like checking your rearview mirror after you've already passed the exit. Monthly P&L reviews, even quick ones as part of your monthly financial review checklist, let you catch trends while there's still time to respond.
Mixing Personal and Business Expenses on the P&L
If personal expenses end up in your business P&L, your profit number will look lower than it actually is. And if you're using that inaccurate number to make business decisions, you're operating with bad data. This is one of the biggest reasons to separate business and personal finances with clean categories and dedicated accounts.
Ignoring Small Recurring Charges
A $29/month software subscription doesn't look like much on its own. But if you have 12 of them and you're only actively using six, that's $2,088 per year in spending that isn't serving your business. Your P&L makes these visible when your categories are specific enough to show each one individually.
The Difference Between a P&L and a Balance Sheet
People sometimes confuse these two documents, so it's worth a quick clarification.
A profit and loss statement covers a period of time. It tells you what happened during that month or quarter or year. How much did you earn? How much did you spend? What was left over?
A balance sheet covers a moment in time. It tells you what your business owns (assets), what it owes (liabilities), and the difference between the two (equity) on a specific date.
Think of the P&L as a movie. It shows you the story of what happened over time. The balance sheet is a photograph. It captures a single moment.
Both documents are valuable. But for most small business owners, the P&L is the document you'll look at most frequently because it directly answers the question: is my business making money?
How a Financial System Makes Your P&L Easier to Read
If you're building your P&L manually from bank statements and receipts, the process can take hours. And the result is only as good as your categorization. If you've been tossing everything into "Expenses" all month, your P&L will have one giant line item that tells you almost nothing.
This is where a structured financial system changes the experience entirely. When you categorize transactions throughout the month, your P&L builds itself. You don't have to create it from scratch at month-end. You just review what's already there.
Money Mastery generates profit and loss reports automatically based on the categories you've been using all month. Because the system has over 400 expense categories and Clarity AI helps sort transactions as they come in, the P&L you get is detailed, accurate, and ready to review without any extra work. You can also share that report directly with your accountant through the built-in share function, which means less back-and-forth and potentially lower professional fees.
Start Reading Your P&L With Confidence
A profit and loss statement for small business owners isn't meant to be intimidating. It's meant to be informative. Once you understand the four sections (revenue, COGS, operating expenses, and net profit) and know what to look for (revenue trends, largest expenses, and profit margin), the P&L becomes one of the most useful documents in your financial life.
Here's your action step for today. If you already have a P&L, pull it up and identify your top three expense categories and your net profit margin. If you don't have one yet, use the P&L snapshot template in the Net Worth Tracker to build a basic version using last month's numbers. Either way, you'll walk away understanding your business better than you did 15 minutes ago.
Tomorrow, we'll tackle a question that every business owner asks at some point: how much does a bookkeeper cost, and when is the right time to consider professional financial support?
What a Profit and Loss Statement Actually Looks Like, Line by Line
It is easier to read a P&L when you have seen one. Here is a simple month for a two-chair salon, laid out the way almost every profit and loss statement is laid out.
| | |
|---|
| | Money from the work you do |
| | |
| | |
| | |
| | |
| | What the work itself consumed |
| | Revenue minus the cost of product |
| | |
| | |
| | |
| | |
| | |
| | |
| | |
Revenue sits at the top: Services 5,340, Retail 1,650, Gift cards 920, Tips 600, for total revenue of 8,510. Underneath it comes cost of goods sold, the cost of the things you sold: colour and product, 2,100. Subtract that and you get gross profit, 6,410. That is the money the business actually generated before any of the fixed costs of being open.
Then operating expenses, one line each: booth and rent 1,850, card processing 770, marketing 590, insurance 490, software 180. Those total 3,880. Subtract them from gross profit and you land on net profit: 2,530. That single number at the bottom is what the whole page exists to produce.
Read in that order, a P&L is a story in four steps. Money in, cost of delivering it, cost of existing, what survived. If you can find those four lines on your own statement, you can read any profit and loss statement you are ever handed, no matter how many rows it has or which software produced it.
How to Read a P&L Report Month Over Month
To read a P&L report month over month, put two statements side by side and compare four lines only: total revenue, gross profit, total operating expenses, and net profit. Read each one as a percentage of revenue rather than as a dollar figure. Dollars move with how busy you were. Percentages show whether the business itself changed.
A single month tells you very little on its own. Revenue looks strong in a month one large client paid early. Expenses look low in a month an annual insurance bill has not landed yet. Comparison is what turns a statement into a report you can act on.
Each comparison points somewhere specific. If revenue rose and your net profit percentage fell, you grew and kept less of it, which usually means a cost rose alongside volume. If revenue fell and your net profit percentage held steady, your costs are flexing correctly and the business is behaving. If both fell, open your largest expense category first, because that is where the money went.
Three months is the shortest window worth trusting. Two months can be explained away by timing. Three shows direction. Rising and Thriving recommends reading the P&L on the same day each month, right after the month closes, so every comparison is like for like. If you are heading into year end, that same month-over-month read is the first step in what to do in Q4 so tax season is not a crisis.
Frequently Asked Questions
What is a profit and loss statement in simple terms?
A profit and loss statement is a document that shows how much money your business earned (revenue), how much it spent (expenses), and whether you ended up with a profit or a loss over a specific period. It's essentially a scorecard for your business operations. Most small business owners review their P&L monthly or quarterly to understand how their business is performing financially.
How often should a small business owner review their P&L?
Monthly is ideal. A monthly P&L review gives you enough data to spot trends, catch expense creep, and make adjustments before small issues become expensive problems. If monthly feels like too much at first, start with quarterly and work your way up. The more consistently you review it, the faster and easier the process becomes.
What is the difference between a P&L and a cash flow statement?
A P&L shows whether your business is profitable by comparing revenue to expenses over a period of time. A cash flow statement shows how money actually moves in and out of your accounts, including things like loan payments, owner's draws, and transfers that don't appear on a P&L. You can be profitable on your P&L and still be short on cash if your clients pay late or you have large debt payments. Both documents serve different purposes.
Can I create my own profit and loss statement without an accountant?
Yes. A basic P&L requires three things: your total revenue, your total expenses broken into categories, and the difference between them (net profit or loss). You can build one in a spreadsheet or use a system like Money Mastery that generates P&L reports automatically based on your categorized transactions. Having your own P&L also makes working with an accountant faster and less expensive because they spend less time organizing your data.
What is a good profit margin for a small business?
Profit margins vary significantly by industry. Service-based businesses often see net margins between 15% and 40%. Product-based businesses with higher material costs might operate between 5% and 20%. There's no single "right" number. What matters most is that you know your margin, track it monthly, and watch for trends. A shrinking margin over several months deserves attention regardless of where it started. This is general information, not financial advice.
If you would like to talk it through with someone, Donna Roggio is a business coach with fifteen years of experience helping women sort this out, and a first call with her is free.
What does a profit and loss statement look like?
A profit and loss statement is a single page in four stacked blocks. Revenue at the top, listed by source. Cost of goods sold beneath it, which is what it cost to deliver what you sold. Operating expenses next, one line per category. Net profit at the bottom, which is revenue minus everything above it. Most statements also show a percentage column so you can see each line as a share of revenue.
How do you read a P&L for the first time?
Ignore every row except four. Find total revenue, find gross profit, find total expenses, and find net profit. Ask whether revenue is going up, whether your largest expense is earning its place, and whether the net profit is enough to pay you. Everything else on the statement is supporting detail you can come back to once those four make sense.
How do you read a P&L report?
Read four lines in order: total revenue, gross profit, total operating expenses, and net profit. Then read each as a percentage of revenue. Then compare those percentages to last month. A P&L report is only useful in comparison, because a single month is a snapshot rather than a trend.
What should a P&L report show month over month?
It should show the same line items for each month side by side, plus each line as a percentage of revenue. Look for a net profit percentage that is stable or rising. A percentage that falls three months in a row means a cost is growing faster than revenue, even when the dollar profit still looks acceptable.