


The Difference Between a Tax Bill and a Cash Flow Problem
A business can be profitable and unable to pay its bills at the same time, and the two things are not a contradiction.
Profit is what you earned. Cash is what has arrived. When you invoice in March and get paid in May, March was profitable and March could not pay anybody.
This matters in October because the two problems look identical from the inside and need opposite answers.

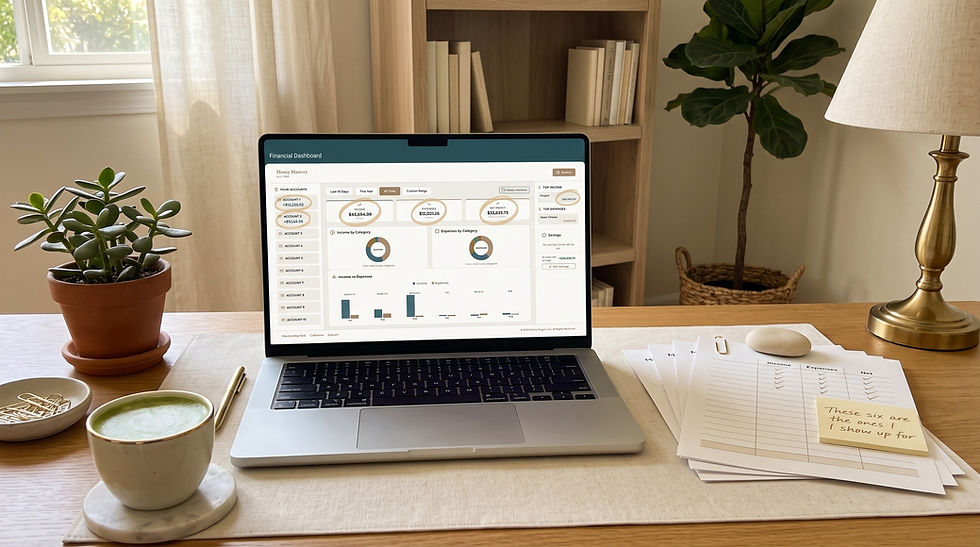
The Money Mastery System dashboard showing profit and cash side by side. Example data.
The short version
Profit is what you earned. Cash is what has arrived. They can be months apart.
If the money is coming, you have a timing problem. If it is not, you have a profit problem.
Timing is fixed with deposits, shorter terms and a buffer. Profit is fixed with price, mix and costs.
Tax is worked out on profit, so move the set-aside when the cash lands.
One business, six months
A service business invoicing on 60 day terms. Profitable every single month.
Month | Invoiced | Cash in | Costs paid | Profit that month | Cash in hand |
|---|---|---|---|---|---|
January | $9,000 | $4,000 | $5,500 | $3,500 | $1,500 |
February | $11,000 | $4,500 | $6,000 | $5,000 | $0 |
March | $12,000 | $9,000 | $6,500 | $5,500 | $2,500 |
April | $8,000 | $11,000 | $6,000 | $2,000 | $7,500 |
May | $13,000 | $12,000 | $7,000 | $6,000 | $12,500 |
June | $10,000 | $8,000 | $6,500 | $3,500 | $14,000 |
Six months, $25,500 of profit, and in February there was nothing in the account. Nothing went wrong. The money was simply sixty days behind the work.
Which problem do you have?
One question tells you.
Is the money coming, or is it not there?
If it is coming, it is a timing problem. The work was done, the profit is real, and the gap is the wait. Timing problems are solved with terms, deposits and a buffer.
If it is not coming, it is a profit problem. You are not earning enough to cover what you spend. A profit problem cannot be fixed with a loan, and borrowing into one makes it worse by adding a payment to a business that already could not carry its costs.
A tax bill you cannot pay is almost always the first honest measurement of which one you have.
Why a tax bill exposes it
Because tax is calculated on profit, not on cash.
The business above owes tax on $25,500 whether or not that money ever sat in the account. If the set-aside was not moved out as the cash arrived, it was spent on ordinary things in an ordinary way, and the bill arrives for money that is genuinely gone.
That is not a tax problem. It is the timing problem, showing up somewhere it cannot be ignored.

The set-aside filling as income is categorized. Example data.
What actually fixes each one
Timing problem | Profit problem |
|---|---|
Deposits up front, or milestone billing | Raise prices |
Shorter payment terms, and chase on day one | Drop the work with the worst real hourly rate |
A buffer account holding one month of costs | Cut a fixed cost, not a variable one |
Tax moved out on the day money lands | Understand the margin before adding volume |
The left column is administration. The right column is a decision. Doing the left when you needed the right is the most expensive mistake in this post.
How big a buffer closes the gap
Go back to the six months above. Costs averaged $6,250 a month, and the account touched zero in February.
Without a buffer | With one month of costs held back | |
|---|---|---|
Cash in hand at the end of February | $0 | $6,250 |
Lowest point in the six months | $0 | $6,250 |
One month of costs would have turned the worst moment of the half year into an ordinary one. Nothing else about the business needed to change.
Building it does not take a windfall. Cash in over those six months came to $48,500. Holding back 10% of each payment as it arrived would have put $4,850 aside by June, most of the way there, from a business that felt as if it had nothing to spare.
See both numbers at once, free
Most owners can find one of these two numbers and not the other, which is precisely why the problems get confused.
La Soglia, the free membership of the Money Mastery System, holds what you own and what you owe in one place, personal and business together, no bank connection and no card. The monthly view that puts profit and cash beside each other, the way the table above does, is what the paid membership builds from your own transactions.
Bring it to the Collective
The question is the money coming or is it not there is much easier to answer with somebody else asking it. The Money Mastery Collective discussion feed is open on the free membership.
Questions we hear
Can I have a cash flow problem and a profit problem at once?
Yes, and it is common. Fix the timing first, because it is faster, then you can see the profit problem clearly instead of guessing at it.
Does an accountant fix this?
An accountant will tell you which one you have. Only you can change the terms or the prices.
Should I borrow to cover a gap?
For a timing problem with money genuinely arriving, sometimes. For a profit problem, no. Our post on whether to take a business loan has the three tests.
What if my client just pays late?
That is a timing problem you have inherited rather than chosen. Deposits and day one chasing are the two things that move it.
Can a profitable business run out of cash?
Yes. Profit counts work when it is invoiced and cash counts it when it is paid. A gap between the two can empty the account in a profitable month.
How much of a cash buffer should a small business keep?
One month of costs is a common place to start. In the example above that is about $6,250.

Start free with La Soglia
La Soglia is the free membership of the Money Mastery System. It gives you the Net Worth Tracker, where everything you own and everything you owe sits in one place, and the Money Mastery Collective. There is no card to enter and no bank connection.
Keep in touch
Donna shares a short version of posts like this one on Instagram and LinkedIn. Follow along there, or find everything in one place on our links page.
A note on what this is
This article is educational. The Money Mastery System is an educational tool, not financial software, and nothing here is legal, tax, investment or financial advice. The six month table is a worked example, not a typical business. For guidance on your own circumstances, please speak with a qualified professional who knows them.
Comments